
Part of Investor presentation examples · Japanese investor presentation examples
Eisai H1 FY2026 Earnings Presentation: a 33-page Japanese-language investor deck (決算説明会資料 style briefing, cover title 2026年度第2四半期(中間期)決算説明会) whose original was published on TDnet (Tokyo Stock Exchange timely disclosure) on November 10, 2026. It covers the second quarter (interim period) of FY2026, where FY2026 = fiscal year ending March 2027 and H1 = April-September 2026, for Eisai Co., Ltd., a Japanese pharmaceutical company reporting under IFRS in ¥100 million (億円) units.
Uses this deck’s cover as a style reference for slides made from your own content. Or pick any page below to use its layout as the reference.
Quick Navigation
Tags
Share the slides
Eisai H1 FY2026 Earnings Presentation: a 33-page Japanese-language investor deck (決算説明会資料 style briefing, cover title 2026年度第2四半期(中間期)決算説明会) whose original was published on TDnet (Tokyo Stock Exchange timely disclosure) on November 10, 2026. It covers the second quarter (interim period) of FY2026, where FY2026 = fiscal year ending March 2027 and H1 = April-September 2026, for Eisai Co., Ltd., a Japanese pharmaceutical company reporting under IFRS in ¥100 million (億円) units.
Detailed view of each slide page, including layout, key content and visual elements.
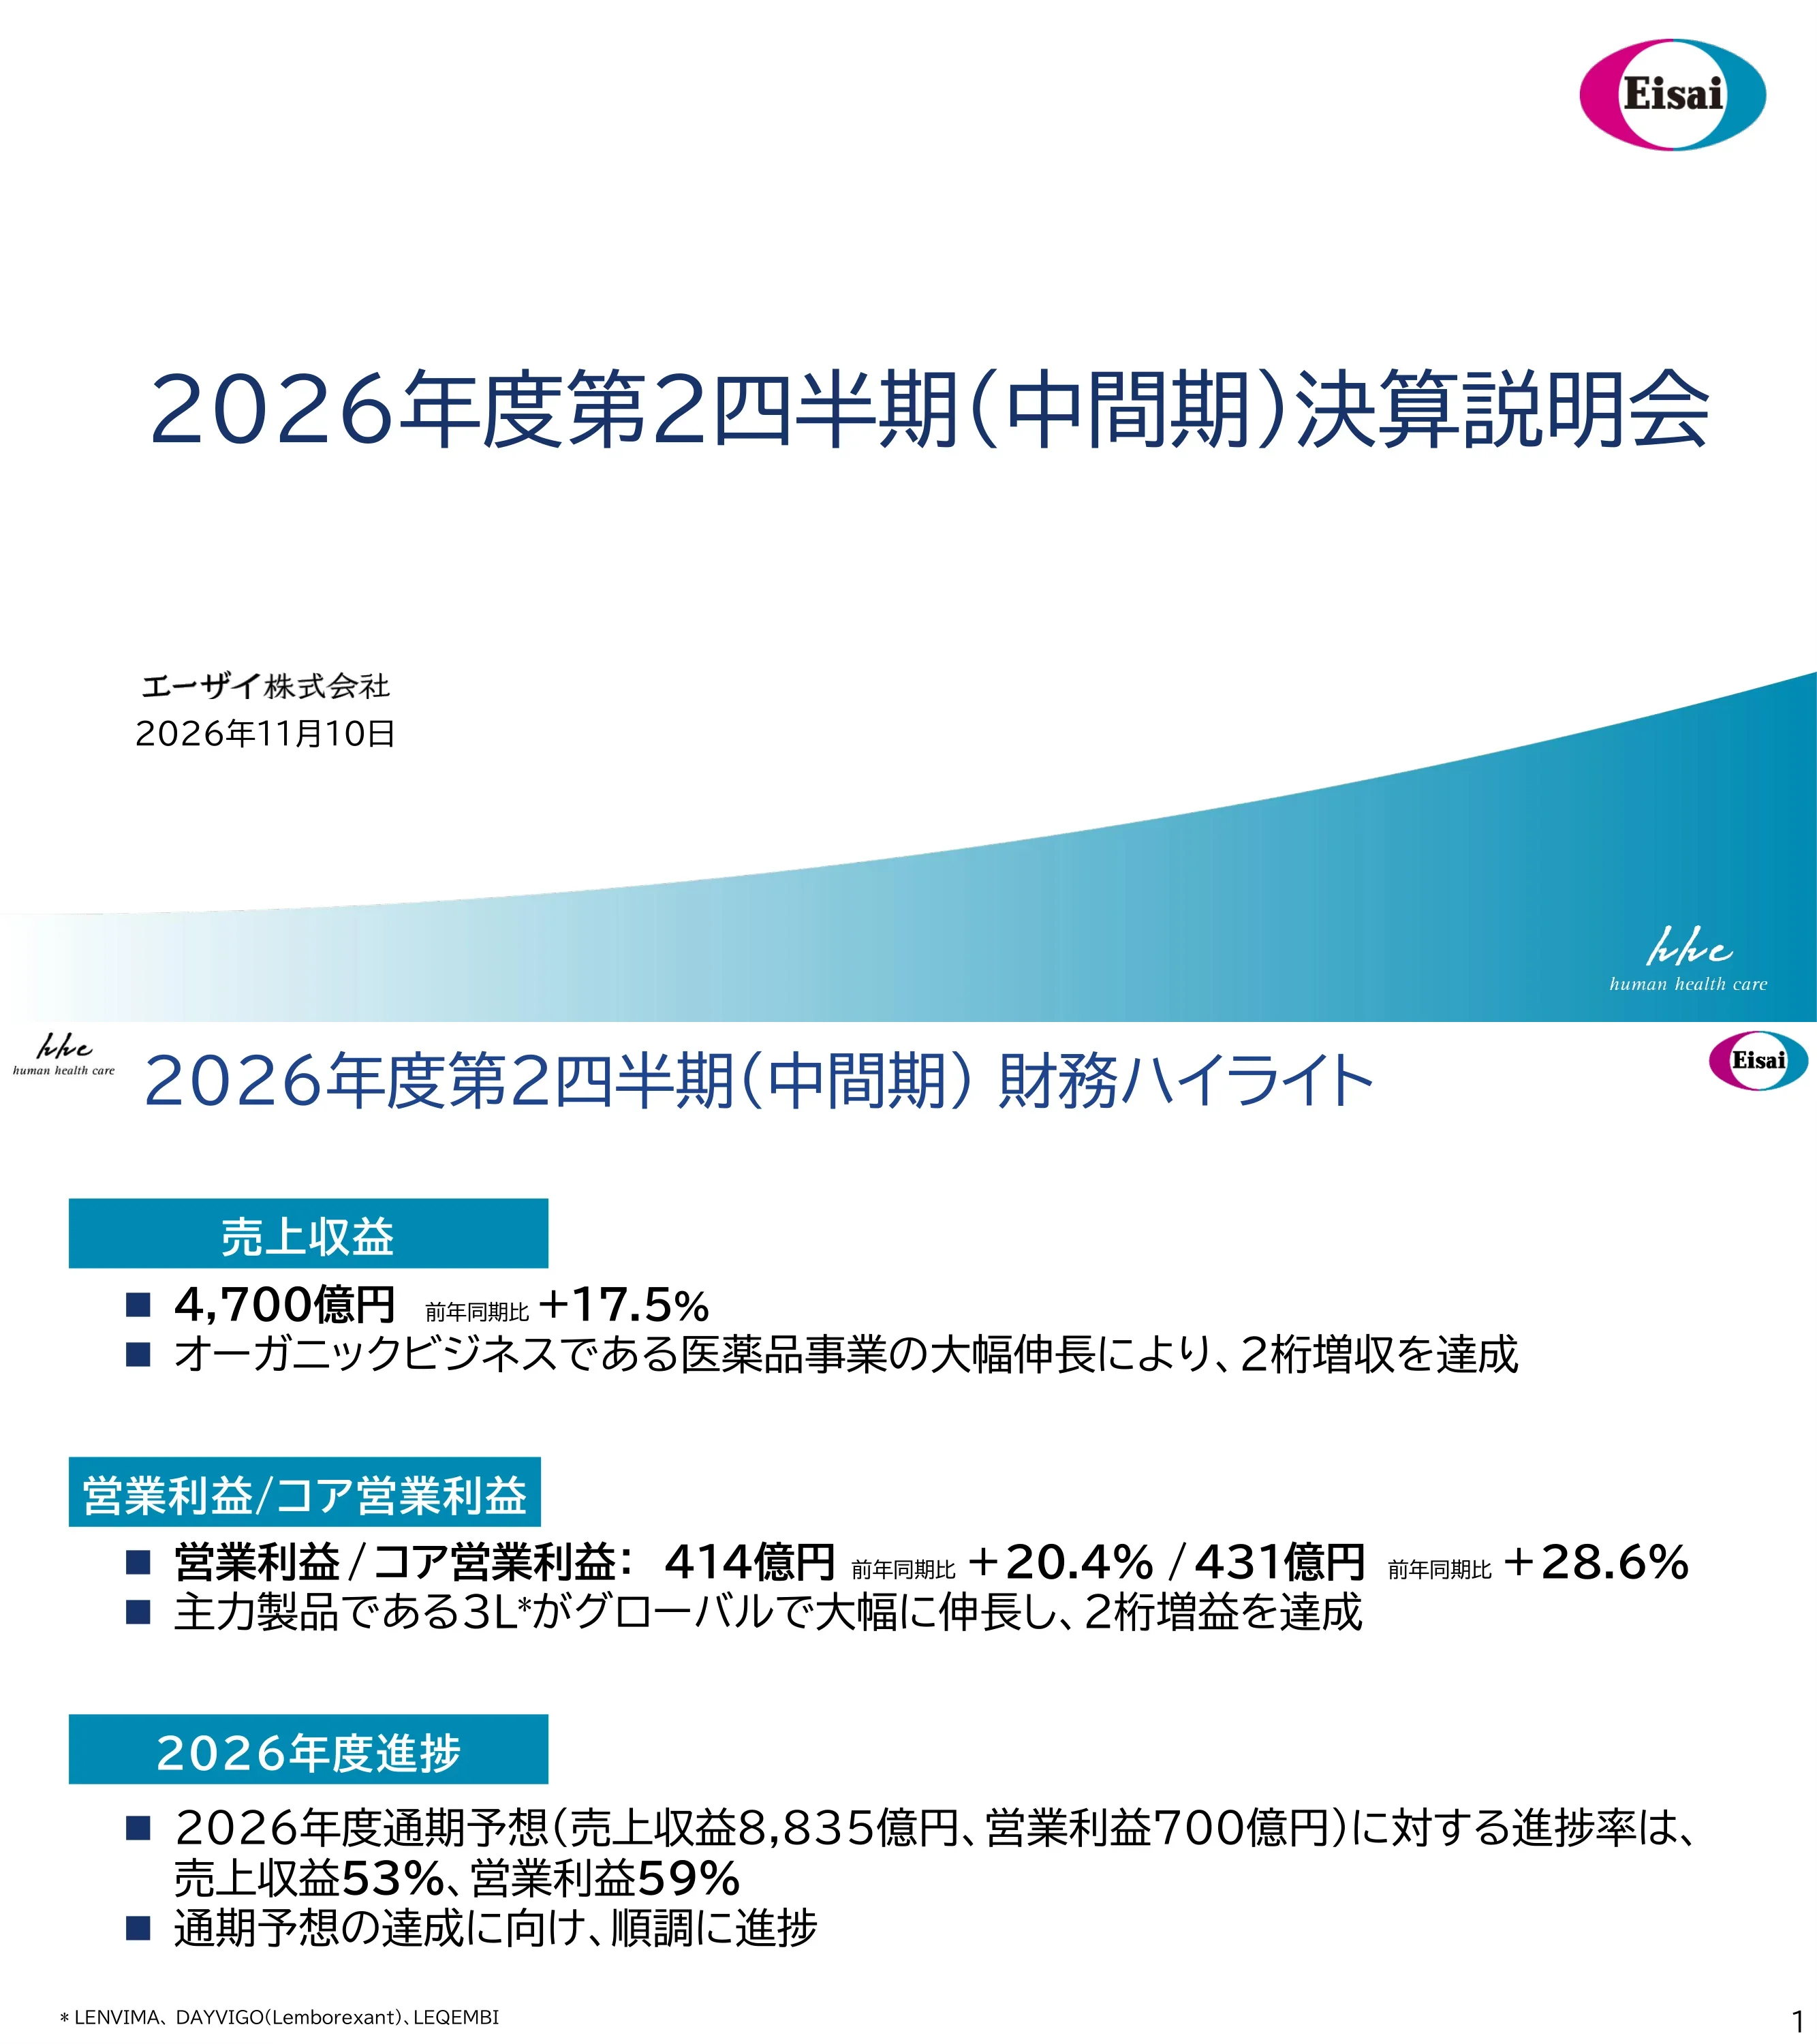
Cover reading 2026年度第2四半期(中間期)決算説明会 (FY2026 Q2 interim earnings briefing), issued by Eisai Co., Ltd. (エーザイ株式会社) and dated November 10, 2026.
Large centered navy title, company name and date at lower left, Eisai logo at top right, teal curved gradient band along the bottom with the 'hhc human health care' mark.
Revenue was ¥470.0 billion (4,700 億円, +17.5% YoY), driven by organic growth in the pharmaceutical business. Operating profit / core operating profit were ¥41.4 billion (+20.4%) and ¥43.1 billion (+28.6%), led by the 3L products LENVIMA, DAYVIGO and LEQEMBI. Progress against the full-year forecast (revenue ¥883.5 billion, operating profit ¥70.0 billion) is 53% for revenue and 59% for operating profit.
Three stacked sections, each with a teal label bar on the left and bold bullet text below; footnote naming the 3L products.
Table comparing H1 FY2025 and H1 FY2026 (¥100 million): revenue 4,000 to 4,700 (+699, +17.5%), gross profit 3,119 to 3,654, R&D 755 to 881, SG&A 2,040 to 2,352, operating profit 344 to 414 (+20.4%), core operating profit 335 to 431 (+28.6%), profit attributable to owners 246 to 299 (+21.5%), EPS 87.37 to 106.18 yen. Full-year forecast and progress-rate columns are included (e.g. revenue 8,835, 53.2%).
Two bullet lines on top, then a dense financial table with the FY2026 H1 column outlined in magenta; footnote explains core operating profit.
Revenue rose by ¥69.9 billion (+17.5%) from 4,000 to 4,700. The 3L products contributed +591, other pharmaceutical products +97 and other businesses +12. Within 3L: LENVIMA +282 (+17%), DAYVIGO +104 (+36%), LEQEMBI +204 (+50%). Pharmaceutical revenue was 4,621.
Waterfall chart with start and end bars at the sides, floating increase bars in the middle, a header box showing the total change, and a callout box detailing the 3L increments.
Operating profit rose from 344 to 414 (+70, +20.4%); core operating profit from 335 to 431. Gross profit contributed +535, offset by R&D -126, SG&A -312 and other income/expense -27. Operating margin moved from 8.6% to 8.8%. Notes cite a 142 increase in LENVIMA profit-share expense and a 77 increase in LEQEMBI spending.
Waterfall chart from FY2025 H1 to FY2026 H1 with positive bars in light blue and negative bars in grey, annotation boxes under each driver, and margin pills on the end bars.
LENVIMA revenue was 1,948 (+17% YoY vs 1,665): Americas 1,359, EMEA 283, China 138, Japan 72, East Asia/Global South 95. The full-year forecast of ¥345.0 billion is expected to be achieved. The slide notes FDA approval in September 2026 of LENVIMA plus Welireg (LITESPARK-011) for renal cell carcinoma after anti-PD-1/PD-L1 therapy, with a pending application in Japan, and cites about 650,000 patients served over 11 years in 83 countries and regions.
Left: two-column stacked bar chart by region; right: headline message and two bullet blocks; top banner boxes summarize the drug and its track record; dense footnotes.
Left side covers the first-line RCC combination of LENVIMA plus Keytruda, described as the largest growth driver and top share within IO-IO and IO-TKI combinations. A table shows US prescription six-month average growth rates: total 6.9%, renal cell carcinoma 8.6%, endometrial 6.3%, thyroid 4.6%, hepatocellular 7.9%. Right side shows LITESPARK-011 progression-free survival curves for LENVIMA plus Welireg vs cabozantinib.
Two framed panels: left with bullets and a small table (RCC row highlighted), right with bullets and a Kaplan-Meier curve; footnotes at the bottom are very small and partly hard to read.
DAYVIGO revenue reached ¥39.5 billion (395, +36% YoY vs 291), on track for the ¥73.5 billion full-year forecast. Japan 250, Americas 77, China 28, EMEA 15, East Asia/Global South 25. Approved for insomnia in 29 countries and regions; applications are pending in the UK and Europe.
Left: stacked bar chart by region for two periods; right: headline and five bullets by region; banner boxes at the top.
LEQEMBI revenue was 615 (+50% YoY vs 411): Americas 327, Japan 130, China 97, EMEA/East Asia/Global South 61. Approved in 53 countries and regions. Subcutaneous autoinjector launches: IQLIK in the US on August 24, a pen approved in Japan on September 16 with listing planned for November 13, and China approval on September 2 with launch preparation for FY2026 Q4. The full-year forecast of ¥143.5 billion is progressing as planned.
Left: stacked bar chart with a note on a one-time distributor stocking effect in China; right: bold bullets about SC-AI launches; top banner boxes.
Text-only statement: LEQEMBI slows progression of Alzheimer's disease by removing Abeta protofibrils and plaque from the brain. Three value points: clinical benefit including improvement with early treatment, sustained slowing of progression with long-term dosing, and an established safety profile.
Centered magenta title, one large navy statement paragraph, and three bullet points below on a plain white background.
Four numbered value pillars: patient and family participation and freedom from infusion (weekly, about 15 seconds per injection, fixed dose, 29-gauge double-taper needle); high convenience; reduced burden on healthcare sites; and good safety (systemic infusion reactions 1.4%, ARIA incidence similar to infusion).
Four horizontal rows, each with a large number, a colored rounded label box in a blue gradient, and bullet details on the right; long footnotes at the bottom.
Shows the US dosing pathway. Initiation: IV infusion every 2 weeks, or IQLIK weekly (two 250 mg injections). After 18 months, maintenance: IV infusion every 4 weeks, or IQLIK weekly (one 360 mg injection, approved August 2025). Patients can switch between administration methods.
Two large rounded boxes (initiation and maintenance) linked by an '18 months later' arrow, with double-headed switch arrows inside each box and a magenta header arrow.
Two line charts over the first 10 weeks after launch compare IQLIK initiation with the IV infusion launch (July 2023): the patient ramp is about 4 times the IV pace and the prescriber ramp about 6 times, at week 10. Based on internal estimates from specialty pharmacy and claims data; axis values are not labeled.
Two side-by-side line charts separated by a vertical divider, each with a headline and bullet above; green vs navy lines; footnotes below.
Left: LEQEMBI US net sales in millions of USD by quarter from FY24 Q4 to FY26 Q2, split between IV infusion and IQLIK, with double-digit growth for six consecutive quarters. Right: number of prescribers rising from roughly 1,700 in Sep'24 to roughly 5,500 in Sep'26 (approximate, read from the chart), with IQLIK maintenance and initiation launch markers.
Two bar charts side by side with numbered headings, trend arrows, launch bubbles and magenta commentary under each.
IQLIK initiation expanded new patient numbers and LEQEMBI holds top share in new AAT prescriptions as of September 2026. A line chart of total AAT patients (April-September 2026) shows LEQEMBI rising above other AAT products (approximately 28,000 vs 19,000 in September, read from the chart). A disclaimer states that no head-to-head trial exists with donanemab.
Left: two numbered text blocks in blue and magenta; right: line chart with two series and an IQLIK launch bubble; disclaimer and footnotes at the bottom.
Coverage from January 2027 is progressing: a new AD disease-modifying drug category was created for pharmacy benefits and IQLIK is listed. About 67% of enrollees are secured for planned January 2027 coverage, and the figure is still rising. The lower panel explains reduced and smoothed patient out-of-pocket burden (MOOP cap of 2,100 USD in 2026, M3P monthly payment plan).
Title and two magenta bullets on top, a highlighted stat box with a large '約67%', and a framed list of four patient cost points below; long footnotes.
Approved September 16, listed on the NHI price list and launched November 13. Price is 27,141 yen per 250 mg pen (reference: IV 200 mg vial 38,910 yen, 500 mg vial 97,277 yen). Four expected benefits: more new patients, reduced burden on medical institutions, more initiating sites, and more follow-up sites.
Centered title and magenta subtitle, then one large bordered panel with a pricing section and a four-item numbered list.
Describes expansion to preclinical AD. AHEAD 3-45 (Phase III): A3 (about 400 participants, amyloid PET primary endpoint) and A45 (about 1,100 participants, PACC5 primary endpoint), data readout FY2028. DIAN-TU ART (Phase IIIb/IV): about 40 participants with dominantly inherited AD, five years of lecanemab, primary endpoint time to clinical progression by CDR-SB.
One large framed panel split into two columns for the two trials, each with design, endpoints and readout bullets; small footnotes.
Etalanetug is an anti-MTBR-tau antibody. Study 202 (Phase II, sporadic early AD, about 100 participants, 24 months, primary endpoint CSF MTBR-tau243) reads out in FY2027. Tau NexGen Trial (Phase II/III, DIAN-TU, about 200 participants, 208 weeks, primary endpoint Tau PET) reads out in FY2028. Both add etalanetug on top of LEQEMBI.
One framed panel with a centered heading and two columns, one per study, each listing target, design, duration, endpoints and readout in magenta.
Ledasorexton is being tested for narcolepsy (NT1/NT2). Left: it is the only seed compound from the in-house library HTS and uses DAYVIGO synthesis know-how; a Phase Ib NT1 study showed strong signals on MWT. Right: Phase II (Study 202), planned 64 participants, once-daily oral dosing at low, mid and high dose for 4 weeks each, primary endpoint MWT mean sleep latency; last patient in is achieved and data readout is expected in FY2026.
One framed panel with two columns: a bullet narrative on the left, trial design bullets on the right; footnotes define abbreviations.
Three red text messages: the organic business progressed above plan on 3L growth and Eisai will manage plan versus actual rigorously in H2; the SC-AI launch lowers barriers to LEQEMBI initiation and maintenance and is expected to greatly increase patient numbers; near-term AD contributions include preclinical AD expansion and etalanetug as a potential world-first tau therapy.
Centered title with three large red centered paragraphs on a white background.
Section divider reading 参考資料 (reference materials) that introduces the appendix tables.
Mostly blank white slide with the title at left and a magenta gradient wave at the bottom right.
Income statement in ¥100 million with percent of revenue, YoY change and full-year forecast progress: revenue 4,700 (forecast 8,835, 53.2%), gross profit 3,654 (54.2%), SG&A 2,352, R&D 881, operating profit 414 (forecast 700, 59.2%), core operating profit 431 (61.5%), interim profit 313, profit attributable to owners 299 (forecast 523, 57.2%). Average H1 FX rates: USD 159.37 yen, EUR 184.35 yen.
Wide table with a grey FY2025 block and a teal FY2026 block with highlighted columns; FX-rate footnotes at the bottom.
Pharmaceutical business revenue 4,621 (+17.5%): Japan 1,167 (+3.7%), Americas 1,792 (+26.5%, of which US 1,730), China 826 (+24.7%), EMEA 437 (+12.6%), East Asia/Global South 399 (+17.0%). Other businesses 79; consolidated revenue 4,700. Forecast progress ranges from 50.0% (Japan) to 59.8% (EMEA).
Table with grey prior-year block and teal current-year block; segment definitions in footnotes.
Pharmaceutical segment profit 1,402 (+29.0%, margin 30.3%): Japan 366 (+8.9%), Americas 466 (+55.6%), China 329 (+25.1%), EMEA 101 (+59.0%), East Asia/Global South 141 (+12.4%). Other businesses 25, R&D -785, parent head-office expenses -228, giving consolidated operating profit 414 (+20.4%). A footnote says LENVIMA profit-share costs paid to Merck are now allocated to segments.
Table with grey prior-year and teal current-year blocks including a profit-margin column; explanatory footnote on the segment change.
3L total 2,958 (+24.9%; forecast 5,620, 52.6%). LENVIMA/Kisplyx 1,948 (+17.0%; forecast 3,450), LEQEMBI 615 (+49.7%; forecast 1,435, 42.9%), DAYVIGO 395 (+35.7%; forecast 735, 53.8%), each split by Japan, Americas, China, EMEA and East Asia/Global South. Angle-bracket values denote local-currency growth.
Long table with three product blocks separated by rules; teal highlighted FY2026 columns; narrow columns make small digits dense.
Japan revenue 1,167 (+3.7%; forecast 2,335, 50.0%): prescription drugs 1,056 (+4.5%), consumer health 111 (-3.2%); segment profit 366 (+8.9%). Top products: DAYVIGO 250, LEQEMBI 130, Zelecka 107, LENVIMA 72, Mobicol 72 (+75.9%), Goofice 49, Methycobal 46; Chocola BB group 80 in consumer products.
Table with top summary rows followed by two product sub-tables (prescription and consumer); footnote marks products handled from EA Pharma.
Americas revenue 1,792 (+26.5%; forecast 3,370, 53.2%), of which US 1,730 (+25.8%). Segment profit 466 (+55.6%). LENVIMA 1,359 (US 1,342 or 842 million USD, +8.7% in USD), LEQEMBI 327 (US 325 or 204 million USD, +54.5%), DAYVIGO 77 (US 36 or 23 million USD).
Table with each product shown in yen and in a second line for US million USD; teal highlighted FY2026 columns.
China revenue 826 (+24.7%; forecast 1,470, 56.2%); segment profit 329 (+25.1%). Products: LENVIMA 138, LEQEMBI 97 (+22.7%), Merislon 96, Methycobal 82, Aricept 54, Cerbex 53, Mionar 50, and DAYVIGO 28 (+173.0%; forecast 45, 62.5%).
Table with revenue and segment profit headline rows followed by a product list; teal highlighted current-year block.
EMEA revenue 437 (+12.6%; forecast 730, 59.8%); segment profit 101 (+59.0%). LENVIMA/Kisplyx 283 (+22.5%; forecast 455), Fycompa 78, DAYVIGO 15 (+183.1%), LEQEMBI 10 (+168.6%).
Short table with headline rows and four product rows on a mostly empty slide; same teal/grey column scheme.
Revenue 399 (+17.0%; forecast 795, 50.1%); segment profit 141 (+12.4%). Products: LENVIMA 95, Aricept 72, LEQEMBI 51 (+170.8%; forecast 115, 44.3%), DAYVIGO 25 (+85.7%; forecast 55, 46.3%), Methycobal 24, Pariet 22, Halaven 18, Fycompa 12.
Table with headline rows and a product list; teal highlighted current-year block.
Table grouped by Amyloid, Tau, Neurodegeneration, orexin platform and oncology. Examples: LEQEMBI SC-AI initiation approved in the US (July), China and Japan (September), maintenance approved in the US (360 mg); AHEAD 3-45 topline FY2028; etalanetug Tau NexGen topline FY2028 and Study 202 FY2027; ledasorexton Phase II topline FY2026; LENVIMA RCC second-line approved in the US (September) with Japan approval expected in FY2026; taletrectinib (ROS1 inhibitor) EU launch expected FY2027. Footnotes are very small.
Full-slide table with navy header rows per therapeutic area, colored left labels (A, T, N) for the ATN continuum, and columns for indication, stage and key events.
Standard disclaimer: targets in the material are not formal forecasts (see the annual earnings release under Tokyo Stock Exchange rules), forward-looking statements involve risks and uncertainties, Eisai has no obligation to update them, and consolidated financial statements are disclosed under IFRS.
Single light-blue framed text box with six square bullet paragraphs under the title bar.
Common questions about this slide and the underlying presentation content.
It covers Eisai's results for the second quarter (interim period) of FY2026, April-September 2026: financial highlights, revenue and profit bridges, the LENVIMA, DAYVIGO and LEQEMBI franchises, Alzheimer's and oncology pipeline events, and appendix tables by region.
Revenue was ¥470.0 billion (4,700 億円, +17.5% YoY), operating profit ¥41.4 billion (+20.4%) and core operating profit ¥43.1 billion (+28.6%). Progress against the full-year forecast is 53% for revenue and 59% for operating profit.
FY2026 is Eisai's fiscal year ending March 2027, and H1 FY2026 (the interim period or Q2) is April-September 2026. The cover is dated November 10, 2026.
The deck is in Japanese (the cover title is 2026年度第2四半期(中間期)決算説明会, an earnings briefing), and the original was published on TDnet, the Tokyo Stock Exchange timely disclosure service. This gallery page provides English page-by-page analysis.
It has 33 pages: 20 main pages of highlights, results, product and pipeline updates, followed by an appendix divider and tables for the income statement, segments, flagship products by region, pipeline key events and a forward-looking statement notice.
The 3L products LENVIMA (1,948, +17%), DAYVIGO (395, +36%) and LEQEMBI (615, +50%) together contributed +591 to the +699 revenue increase, all in ¥100 million units.
The gallery page offers the deck for viewing and download in the formats provided there. Because the original is a corporate IR document, check Eisai's terms of use before redistributing its content.
Yes. The KPI highlight page, waterfall bridges, stacked regional bar charts with commentary, and highlighted-column financial tables are easy patterns to adapt for your own earnings or IR presentation.

Create Your Own Slides
Turn your ideas into professional presentations in seconds with 2slides AI.
Reference professional designs, choose your style, and generate slides with perfect text rendering. Powered by Nano Banana—start creating your presentation now.
Your AI Agent for slides. Save time, shine faster with intelligent presentation creation.


© 2026 2slides. All rights reserved.