
Hluti af safninu Dæmi um fjárfestakynningar
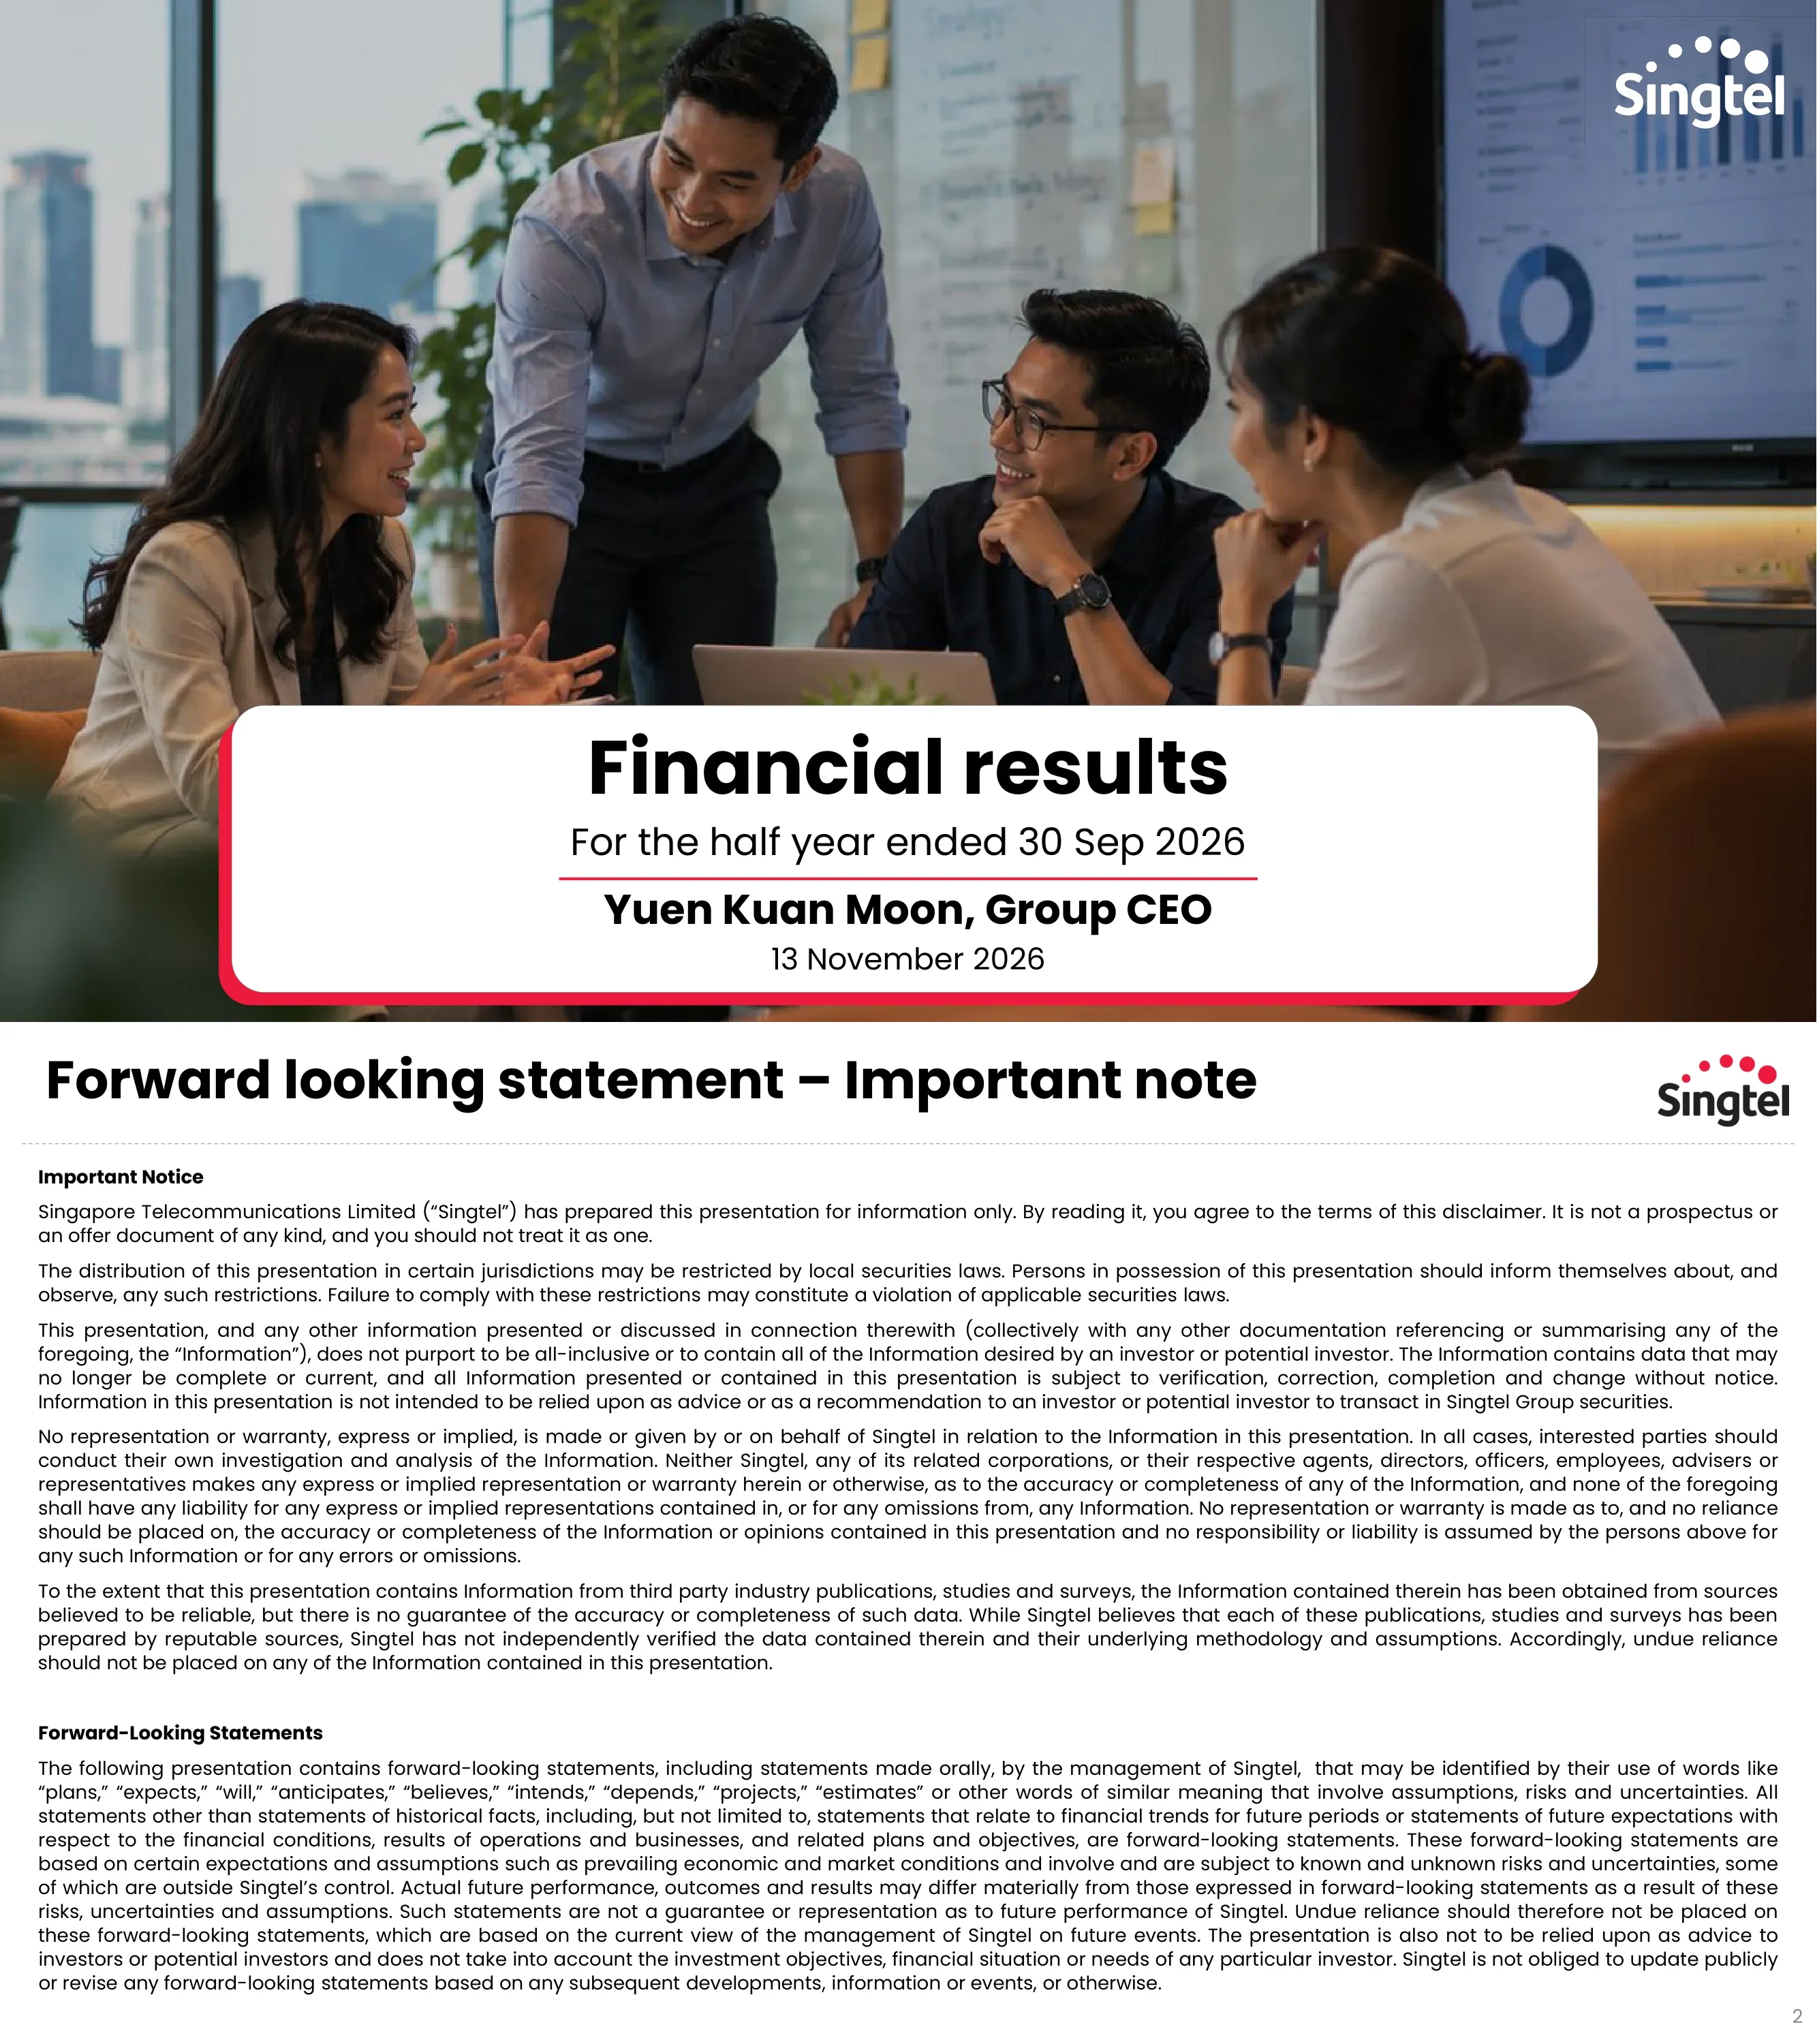
Singtel H1 FY2027 Results Presentation — Singtel's financial results for the half year ended 30 Sep 2026, presented by Group CEO Yuen Kuan Moon on 13 November 2026 and lodged with SGX (Singapore Exchange), showing operating revenue of S$ (Singapore dollars) 7.3B, OpCo EBIT up 9%, an interim dividend of 9.0 cents per share and a raised FY27 OpCo EBIT growth outlook.
Notar forsíðu þessarar kynningar sem stílfyrirmynd fyrir glærur úr þínu eigin efni. Eða veldu hvaða síðu sem er hér fyrir neðan og notaðu uppsetningu hennar sem fyrirmynd.
Flýtileiðsögn
Merki
Deila glærunum
Singtel H1 FY2027 Results Presentation — Singtel's financial results for the half year ended 30 Sep 2026, presented by Group CEO Yuen Kuan Moon on 13 November 2026 and lodged with SGX (Singapore Exchange), showing operating revenue of S$ (Singapore dollars) 7.3B, OpCo EBIT up 9%, an interim dividend of 9.0 cents per share and a raised FY27 OpCo EBIT growth outlook.
Ítarleg sýn á hverja glærusíðu, þar á meðal útlit, lykilefni og sjónræna þætti.
Title slide for the financial results for the half year ended 30 Sep 2026, presented by Yuen Kuan Moon, Group CEO, on 13 November 2026.
Full-bleed photo of colleagues in a meeting room with a white rounded title card with a red edge across the bottom; Singtel logo top right.
Standard disclaimer: the presentation is for information only and is not a prospectus or offer; no representation or warranty is given; third-party data is not independently verified; forward-looking statements are subject to risks and Singtel is not obliged to update them.
Text-only slide with two bold headings, Important Notice and Forward-Looking Statements, each followed by dense justified paragraphs.
OpCo EBIT increased 9% (6% constant currency), at the top end of FY27 guidance. Underlying NPAT grew 10% (16% constant currency) while net profit was 55% lower because of one-off divestment gains in H1FY26. The STT GDC acquisition completed with combined operating capacity of ~950MW (+32% YoY); interim dividend 9.0cts (+10%), ~S$1.0B of shares bought back and FY27 OpCo EBIT guidance raised.
Four stacked rounded cards, each with a red icon on the left, a red headline and bullet points; footnotes in two columns at the bottom.
Operating revenue S$7.3B (+6%, +1% constant currency); EBITDA S$2.1B (+8%, +4%); OpCo EBIT S$0.9B (+9%, +6%); regional associates' PAT S$1.0B (+9%, +17%); underlying net profit S$1.5B (+10%, +16%); net profit S$1.5B (-55%, -52%). Interim dividend of 9.0cts/share (+10%).
Two-row, three-column grid of KPI tiles, each with a large value and a green or red change arrow, plus a full-width dividend banner below.
Singtel SG: tri-brand strategy delivered two consecutive quarters of growth, ARPU +6%, mobile service revenue +4%, main brand churn down 22%, more than S$0.4B Enterprise TCV won. Optus EBIT +14% with doubled regional 5G upgrades to 1,000 sites. NCS EBIT +16%. Digital InfraCo EBIT +25%, with RE:AI first in APAC to deploy NVIDIA DGX GB300.
Four equal columns, each with a photo header carrying the business logo and theme, then large red statistics, partner logos and short descriptors.
Optus: revenue A$4,028M (-2%), EBIT A$322M (+14%), with 4% ARPU growth from higher mobile pricing. Singtel SG: revenue S$1,840M (-1%), EBIT S$420M (-5%); EBIT stable excluding one-off compensation received last year for a contractual breach.
Two halves split by a dotted divider; each has a logo, two metric tiles (revenue and EBIT with YoY arrows) and bullet commentary below.
NCS: revenue S$1,673M (+10%), EBIT S$212M (+16%), secured bookings of S$1.6B with a book-to-bill ratio of 1.0. Digital InfraCo: revenue S$265M (+22%), EBIT S$51M (+25%), with Nxera revenue up 21% and RE:AI momentum.
Two-panel layout mirroring the core telco slide: logo, revenue and EBIT tiles with YoY arrows, then bullets with sub-bullets.
Nxera total gross capacity of 461MW: 146MW operational, 146MW under construction and 169MW pipeline; 72% contracted of 292MW. By country: SG 120MW and TH 26MW operational; MY 64MW, ID 18MW and TH 64MW under construction. 91% of contracted EBITDA is from Singapore; ~210MW contracted capacity (+73%).
Stacked horizontal capacity bar with a country breakdown beneath, a callout box for DC Tuas margin and KKR funding, a pie chart for contracted EBITDA by country, and five footnotes.
Regulatory developments per country: Singapore's Digital Infrastructure Bill (phased from 2027), Malaysia's DC approval and renewable energy requirements (30% minimum approved Oct 2026) and Thailand's Data Center Operation Management Policy (Cabinet approval 10 Nov 2026). Nxera states it is well positioned, with operational and under-construction projects on track and pipeline power committed or secured.
Banner headline, a two-column table (regulatory developments versus positioning) with one row per country flag, and a development continuity panel with two checkmark boxes.
First 6MW is fully contracted for the next 3-5 years with ~S$600M of contracts secured; ~S$300M capex included in FY27 guidance; ~4MW deployed with EBITDA contribution from Sep-26 and ~2MW on track by Q4FY27. Next 6MW has power secured, ~S$300M capex projected from FY28 and demand-led deployment upon securing >80% contracted capacity. Investment economics: 2-3 years payback, low-to-mid 20s EBIT margin, low-to-mid teens equity IRR.
Two large cards (First 6MW, Next 6MW) with checkmark bullet lists, and a bottom strip showing three investment metrics.
After completion on 31 August 2026, Singtel held an effective ~25% shareholding in STT GDC and equity accounts for its share of results, so H1FY27 reflects one month of contribution. Capacity: 805MW operational (APAC 577MW, UK/EU 228MW), 609MW under construction, 1,334MW pipeline, 2,748MW total gross; 71% contracted of 1,414MW. ~1GW contracted capacity (+51%), 89% billing utilisation, EBITDA growth +24%.
Stacked capacity bar with a break in the pipeline segment, a region sub-bar, three metric boxes along the bottom, and a closing grey banner.
A five-layer stack: NCS (applications and services), Paragon (orchestration), RE:AI (GPUaaS and AIaaS), Nxera and STT GDC (data centres), and regional connectivity (Singtel, Airtel, AIS, Telkomsel, Globe, Optus). Combined operating capacity is ~950MW (+32% YoY) and contracted capacity ~1.2GW (+54% YoY); STT GDC acquisition completed 31 Aug 2026.
3D isometric stack of coloured layers on the left, each linked to a descriptive box with bullets on the right; footnote on submarine cable systems.
Regional associates' PAT rose from S$915M to S$993M (+9%, +17% constant currency), despite an S$81M adverse impact from a stronger SGD. H1FY27 by associate: AIS 262, Globe 106, Telkomsel 218, Airtel India 516, Airtel Africa 106, Airtel BTL -216 (all S$M).
Stacked column chart comparing H1FY26 and H1FY27 with segment labels and YoY change on the right, plus a right-hand panel with a headline tile and commentary per associate.
Net debt S$9.0B (Sep 25: S$8.7B); net debt to EBITDA and associate PBT 1.2x (1.3x); interest cover 17.1x (19.8x); fixed rate debt 86% (86%). Cash balance S$3.6B and average cost of debt ~3.8%. Cash sources were S$3,228M in H1FY27 versus S$3,709M in H1FY26 (-13%), with S$1B of cash recycled this period. Ratings shown: Moody's A1 and S&P Global A+, with S&P's first ratings upgrade noted.
Row of four metric tiles with prior-year comparatives, a stacked horizontal bar chart of FCF components and asset recycling below, and bullet commentary with rating logos on the right.
Ordinary dividends declared FY21 to FY27 in Scts, split into interim, final and value realisation dividend (VRD). FY26 totalled 18.5; FY27 interim dividend is 9.0cts (7.1cts core and 1.9cts VRD), up 10%, at a core payout ratio of 78% of H1FY27 underlying NPAT. S$1.0B of the Value Realisation Share Buyback executed; on track to grow total FY27 dividend by mid to high-single digits.
Stacked bar chart across seven fiscal years with phase labels (Strategic reset, Singtel28) on the left and three summary cards on the right; banner at the bottom.
FY27 OpCo EBIT growth rate guidance is raised from between low and mid-single digits to between mid and high-single digits. Regional associates' dividend S$1.1B and capex S$3.0B (Core S$1.8B, Growth S$1.2B) with S$0.7B to be funded by external capital partners and customer advance receipts. H1FY27 is on track for the first two items, and capex guidance is to be confirmed in Q3FY27, likely lower than current guidance.
Left table card listing guidance items with old versus new values; a red arrow leads to a right card with green checkmarks for H1FY27 status.
Priorities grouped in three bands. Digital connectivity: Singtel SG tri-brand and AI, Optus postpaid additions, and regional associates' cost optimisation. Digital infrastructure: ramp up DC Tuas and RE:AI, scale Nxera, and disciplined capital management at STT GDC. Digital services: NCS AI platforms, Digital Resilience offerings and East-West tech stacks.
Three horizontal bands with vertical side labels, each row pairing a company logo on the left with two or three bullets on the right.
Section divider introducing the appendix slides.
Darkened full-bleed photo of a Singtel reception with blurred walking people and a white title card at the bottom centre.
~65 initiatives across 10 value pools. Return on Customer: 85% customer satisfaction, ~67% faster handling time, >60% AI-led care resolution. Return on Employee: 82% see AI as a key growth lever, 85% building AI-era skills, with 3,000 practitioners and 300 specialists being developed. Return on Future: 60% care interactions with zero human involvement, 80% faster identification of network issues, 30% reduction in time for new software releases, and up to 75% field dispatch efforts reduced.
Red banner headline above three dark-blue columns, each with a header icon, large red statistics, tag pills and an image at the bottom.
NCS reorganises into Strategic Business Groups (gov+, enterprise, telco+) mapped to Industry Operating Groups (Foundation plus Strategic Growth: Defence, Homeland Security, Healthcare, Transport, Overseas Geographical Units). Service Organisations (Applications, Infrastructure, Engineering, Cyber) map to two AI-led service delivery engines: Apps & Comms Engineering and Digital Resilience.
Two numbered horizontal bands with chevrons: the left shows current structure and the right the new AI-led model, with boxes beneath each band.
Closing slide with the Singtel logo and LinkedIn, Facebook and YouTube icons.
Centred logo on a white background with three social icons in the bottom right corner.
Algengar spurningar um þessa glæru og undirliggjandi kynningarefni.
It covers the half year ended 30 Sep 2026 and is dated 13 November 2026. The title slide names Yuen Kuan Moon, Group CEO, as presenter.
Singtel's fiscal year runs from April to March, ending on 31 March. H1 FY27 therefore means the first half of fiscal 2027, April to September 2026. H2 FY27 would be October 2026 to March 2027. SGX-listed companies report full financial statements half-yearly, which is why this deck covers a half year.
It was lodged with SGX (Singapore Exchange), where Singtel is listed, alongside the half-year results announcement.
The headline slide shows operating revenue of S$7.3B (+6%), EBITDA of S$2.1B (+8%), OpCo EBIT of S$0.9B (+9%), regional associates' PAT of S$1.0B (+9%), underlying net profit of S$1.5B (+10%) and net profit of S$1.5B (-55%). The net profit decline is attributed to one-off divestment gains in the prior period.
The interim dividend is 9.0 cents per share, up 10%, made up of a 7.1 cent core dividend and a 1.9 cent Value Realisation Dividend. The deck gives a core payout ratio of 78% of H1FY27 underlying NPAT.
Yes. FY27 OpCo EBIT growth guidance was raised from between low and mid-single digits to between mid and high-single digits. The outlook slide also shows regional associates' dividend of S$1.1B and capex of S$3.0B, with capex guidance to be confirmed in Q3FY27 and likely lower.
It has 21 slides: title and disclaimer, highlights, business segment results (Optus, Singtel SG, NCS, Digital InfraCo), data centre slides for Nxera, RE:AI and STT GDC, an ecosystem overview, associates' PAT, financial position, dividends, outlook and H2 focus areas, then an appendix on AI at Singtel SG and NCS's AI-led structure.
Nxera has 461MW of gross capacity (146MW operational), STT GDC has 2,748MW of gross capacity (805MW operational), and combined operating capacity is ~950MW (+32% YoY). The STT GDC acquisition completed on 31 August 2026.

Create Your Own Slides
Turn your ideas into professional presentations in seconds with 2slides AI.
Sæktu innblástur í faglega hönnun, veldu þinn stíl og búðu til glærur með fullkominni textabirtingu. Knúið af Nano Banana—byrjaðu að búa til kynninguna þína núna.
Þinn AI-þjónn fyrir glærur. Sparaðu tíma, skín hraðar með snjallri kynningargerð.


© 2026 2slides. Allur réttur áskilinn.