
อยู่ในคอลเลกชัน ตัวอย่างงานนำเสนอสำหรับนักลงทุน · ตัวอย่างพรีเซนเทชันนักลงทุนญี่ปุ่น
TOTO H1 FY2026 Earnings Presentation: first-half results for the fiscal year ending March 2027, revised full-year plan, ceramics (semiconductor components) investment plan and shareholder returns. This is a Japanese-language deck (2027年3月期 第2四半期 決算説明資料) dated October 30, 2026, originally published on TDnet, the Tokyo Stock Exchange's timely disclosure system.
ใช้หน้าปกของงานนำเสนอนี้เป็นต้นแบบสไตล์สำหรับสไลด์ที่สร้างจากเนื้อหาของคุณเอง หรือเลือกหน้าใดก็ได้ด้านล่างเพื่อใช้เลย์เอาต์ของหน้านั้นเป็นต้นแบบ
การนำทางด่วน
แท็ก
แชร์สไลด์
TOTO H1 FY2026 Earnings Presentation: first-half results for the fiscal year ending March 2027, revised full-year plan, ceramics (semiconductor components) investment plan and shareholder returns. This is a Japanese-language deck (2027年3月期 第2四半期 決算説明資料) dated October 30, 2026, originally published on TDnet, the Tokyo Stock Exchange's timely disclosure system.
มุมมองรายละเอียดของแต่ละหน้าสไลด์ รวมถึงlayout เนื้อหาหลักและองค์ประกอบภาพ
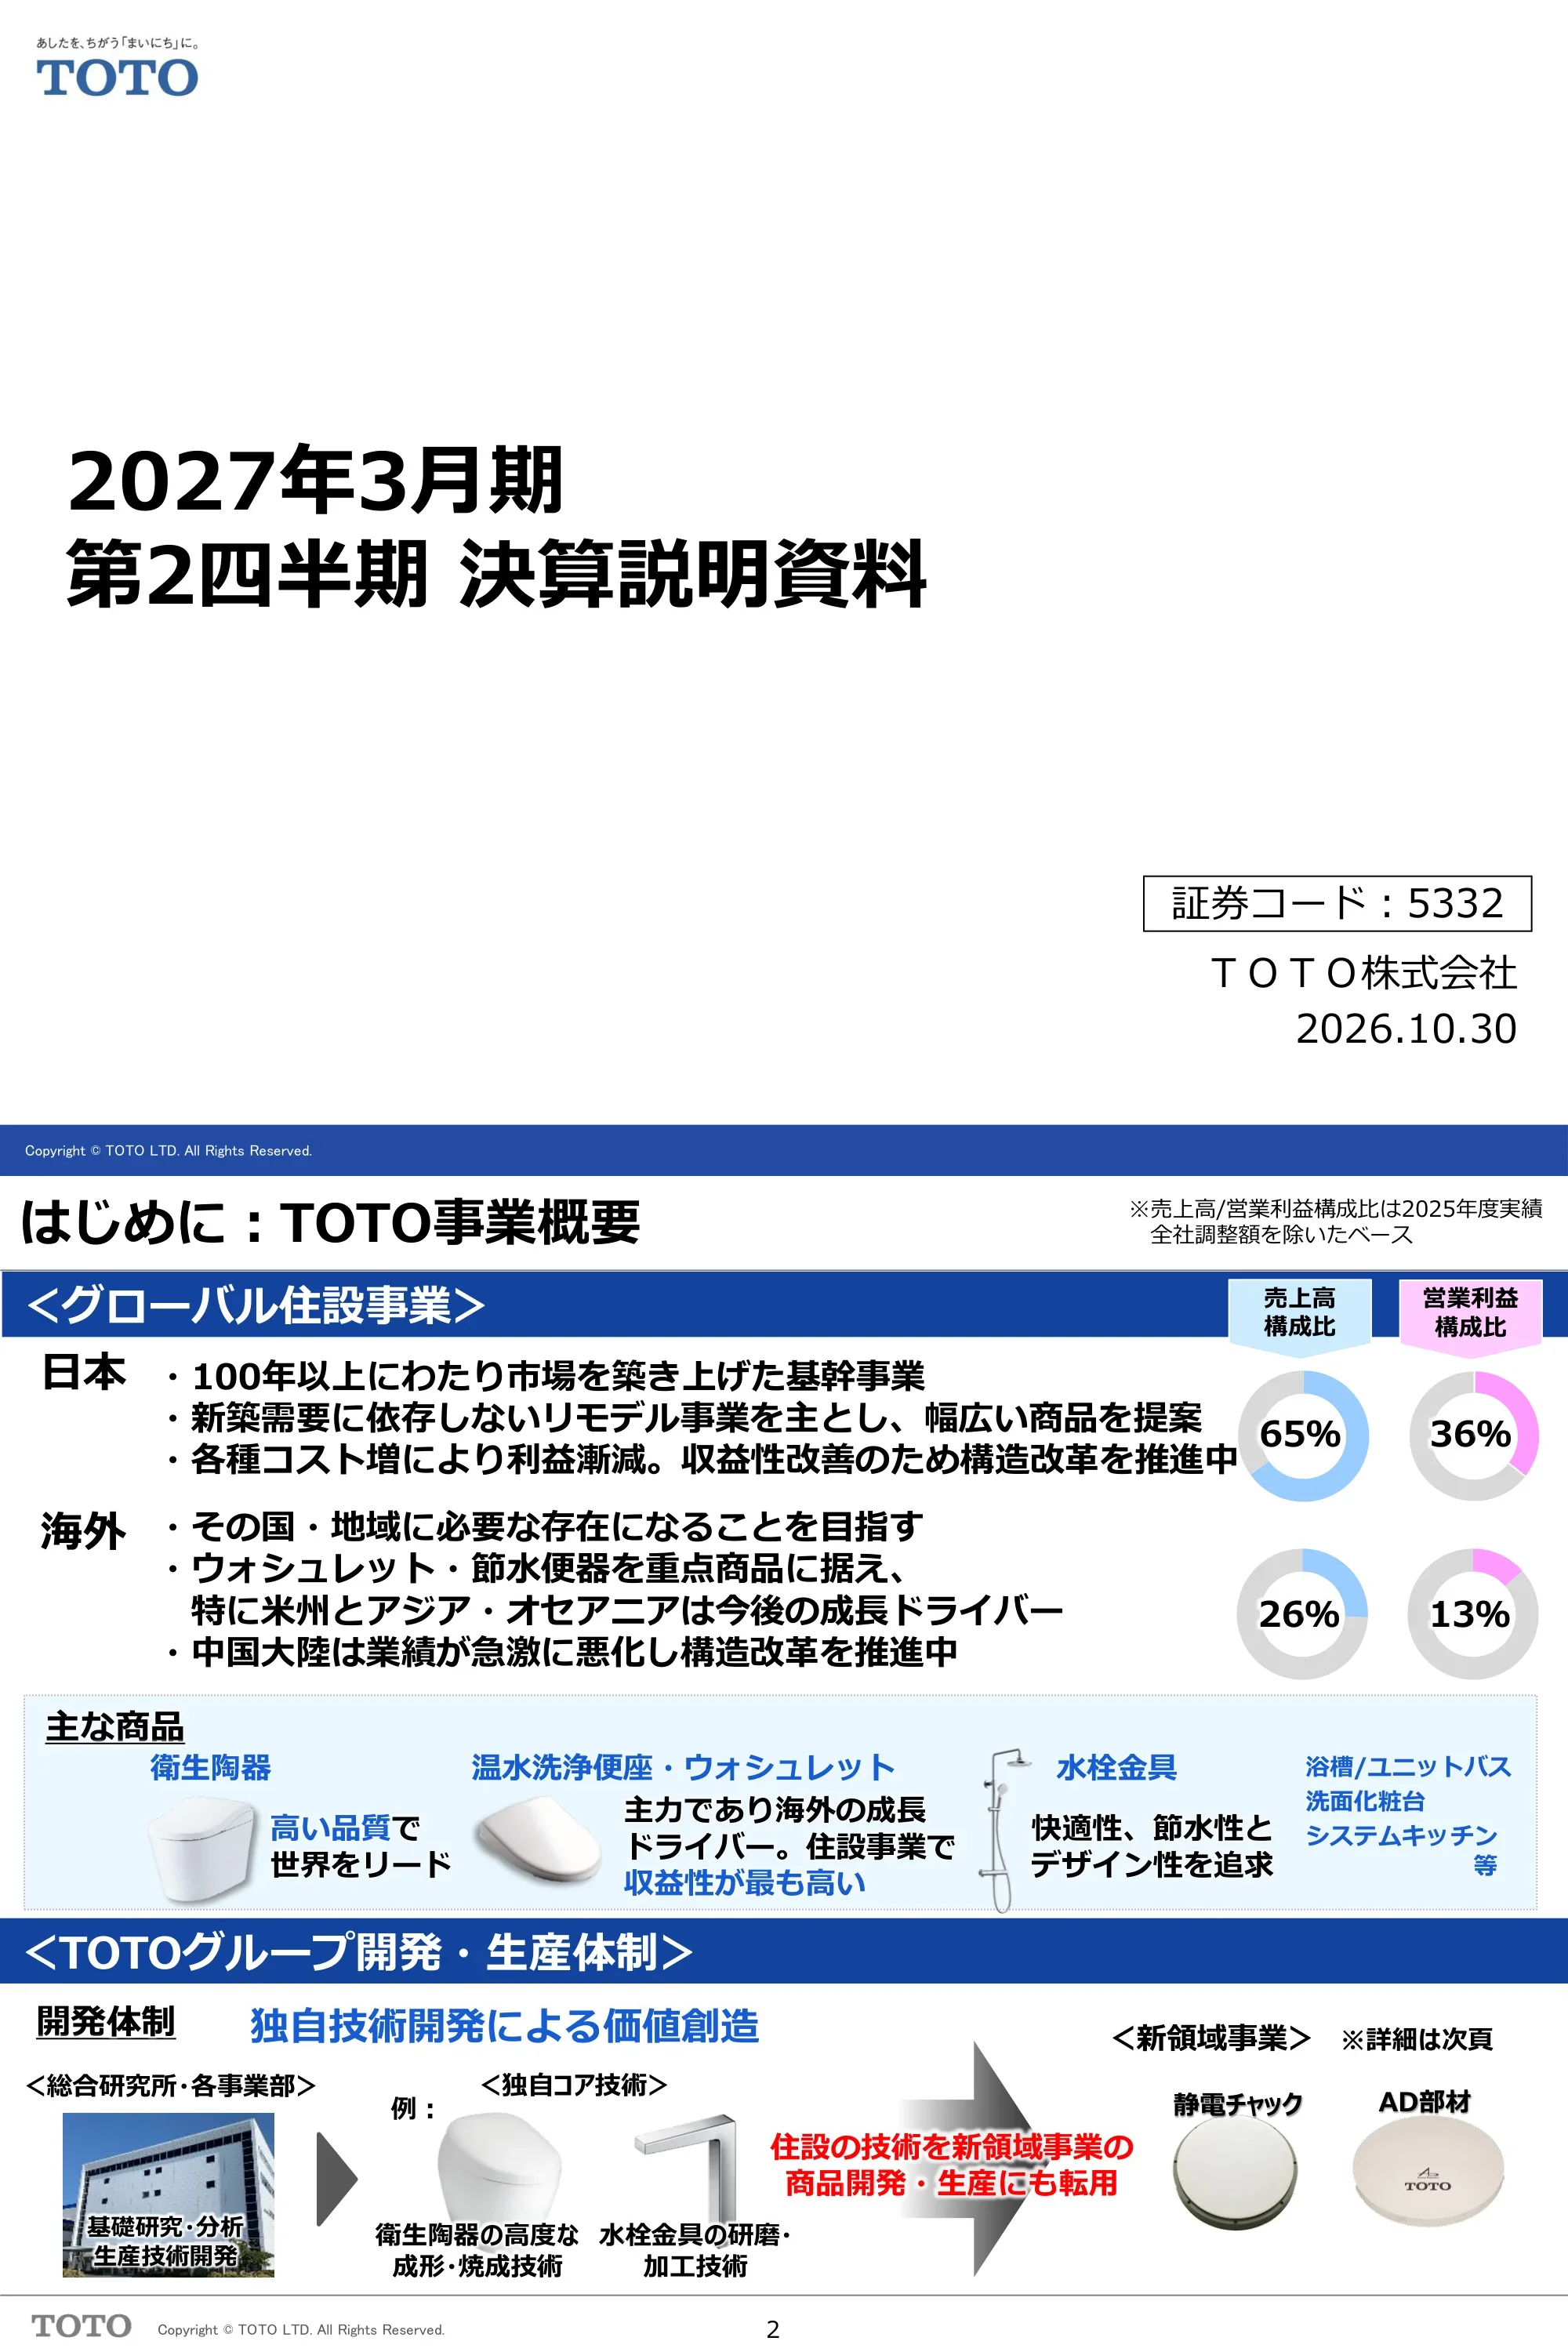
Title slide for the second-quarter (first-half) results of the fiscal year ending March 2027, from TOTO Ltd. (securities code 5332), dated October 30, 2026, with the tagline 'Make tomorrow a different everyday'.
Minimal white cover with logo top-left, large black two-line title on the left, securities code box and company name/date bottom-right, blue footer band
Japan housing equipment, a 100-year-old core business focused on remodeling, accounts for 65% of FY2025 sales and 36% of operating profit and is undergoing structural reform; overseas housing equipment (26% of sales, 13% of profit) targets the Americas and Asia-Oceania as growth drivers while Mainland China is being restructured. Main products are sanitaryware, Washlet warm-water bidet seats (the most profitable housing product), faucets, bathtubs, vanities and kitchens; core ceramics and metal-finishing technology is also applied to the New Domain business.
Two blue section bands; upper band has Japan/overseas bullet text with paired donut charts for sales and profit mix, a light-blue product strip, lower band shows development system flowing via an arrow into New Domain products
The ceramics business makes high-precision ceramic parts for semiconductor manufacturing equipment and contributes 9% of sales but 51% of operating profit. Electrostatic chucks hold wafers and are used in cryogenic etching for NAND flash; AD parts, made with a proprietary aerosol deposition film, are chamber ceiling parts used in logic etching because of high plasma resistance and low particle generation.
Header band with sales/profit donuts (9%/51%), product table with two rows, lower-left chamber cross-section diagram, lower-right value-chain graphic to memory, logic and data centers
Section divider introducing the second-quarter cumulative results for the fiscal year ending March 2027.
Full-bleed blue background with centred white title
Japan housing equipment saw lower sales and profit as Middle East-related sales and supply disruption eased but Q1 bathroom sales fell and procurement costs rose. Overseas housing equipment grew sales and profit: the Americas grew on Washlet and new sanitaryware but swung to a loss on mix and one-off growth investment costs; Asia grew sales but profit fell on unrealised profit from temporary US inventory; Europe grew on Washlet but profit fell on staffing and showroom investment; Mainland China grew on retail and sharply narrowed its loss. The ceramics business grew sales and profit on strong leading-edge semiconductor demand and FX.
Blue headline banner followed by three bold segment headings each with diamond bullet explanations
H1 net sales ¥3,647 億円 vs ¥3,494 (+153, 104%; +38 excluding FX of +115) against a plan of ¥3,700; operating profit ¥252 億円 vs ¥208 (+44, 121%), margin 6.9% (+1.0pt), ¥22 above plan; ordinary profit ¥248 (+17); net profit attributable to owners ¥213 vs ¥88 (2.4x), ¥18 above plan. Average FX for Apr–Sep 2026 was about ¥159–160 per dollar, ¥23.5 per yuan and ¥183–185 per euro. Sales and net profit were record highs.
Main P/L table with prior year, current year (blue highlight), YoY, FX impact, FX-adjusted change, plan and plan variance; FX rate table below; blue conclusion banner
Operating profit rose from ¥208 億円 to ¥252: sales volume/mix +13 (ceramics strong, housing weak), price revisions +69, cost reduction +50, external procurement costs -66 (copper, electronic parts, resin), human capital investment -42, depreciation -8, IT investment -5, R&D/production +4, sales investment +2, FX +26. The Middle East situation hit operating profit by ¥35 億円, ¥10 better than the initial plan.
Waterfall chart with blue increases and grey decreases, callout boxes, a row of variance-to-plan figures underneath, blue conclusion banner
Sales: Japan housing ¥2,231 億円 (98%), overseas housing ¥1,018 (112%), New Domain ¥396 (134%), total ¥3,647. Operating profit: Japan housing ¥54 (81%, but ¥34 above plan), overseas housing ¥30 (106%, ¥25 below plan), New Domain ¥182 (143%), other -14, total ¥252. Overseas covers January–June 2026; prior-year figures restated for a change in common cost allocation.
Two stacked tables (sales and operating profit) with YoY, FX and plan columns, footnotes, blue conclusion banner
Remodel sales ¥1,611 億円 (99%) with operating profit ¥59 (down ¥9); new-build sales ¥620 (94%) with an operating loss of ¥5 (down ¥4). Restroom products were firm, with condominium remodel restroom sales at 110% and public remodel at 107%. New products launched in August 2026 include the Pure Rest EX toilet and GG800 integrated Washlet toilet, with all residential Washlets now instantaneous heating. A price revision is planned for the second half.
Two KPI boxes for remodel and new build, rounded panel with remodel bullets, new-product photo grid and placeholder cards for upcoming launches, conclusion banner
Structural reform measures contribute ¥76 億円 to FY2026 operating profit. The FY2026 bridge goes from ¥219 actual to a ¥130 initial plan (procurement costs -125, Middle East -40, reform +76) and to a ¥145 revised plan with further procurement costs offset by a December 2026 price revision. Reform categories with 2030 targets and FY2026 effect: new value in daily wellness (+20 / +6), resource and product strengthening for target markets (+120 / +17), domestic plant utilisation (+50 / +18), smart and factory automation (+30 / +7), further cost reduction (+120 / +22), DX-based cost structure review (+50 / +6).
Blue headline text top-left, bar-chart bridge top-right, reform category table below with 2030 and 2026 effect columns highlighted in red
Examples include shifting sales staff toward demand areas (20% by FY2026, 40% by FY2030), August 2026 product launches with new-product sales at 125% YoY, merging eight sales companies into TOTO Aqua Marketing, a public remodel team at each branch, focus on remodel-age condominium areas, technical-center consultation events, sanitaryware factory automation, an FX-resilient local production setup, and redeployment of staff to growth segments, with ceramics staffing up 13% in April 2026 and 18% by October 2026 (about half transferred from Japan housing).
Grid of rounded panels: sales map with arrows, product photos, four measure cards with check marks, local production panel and human resource redeployment panel; conclusion banner
Sales: Americas ¥415 億円 (110%), Asia ¥276 (113%), Europe ¥37 (129%), Mainland China ¥290 (112%), total ¥1,018 (112%, ¥16 below plan). Operating profit: Americas -2 (down ¥30), Asia 38 (89%), Europe -2, Mainland China -4 (improved by ¥37 from -41), total 30 vs 28, against a plan of 55. Every region delivered double-digit sales growth.
Two regional tables for sales and operating profit with FX and plan variance columns, footnotes, conclusion banner
Sales $262 million (103%) and operating profit $9 million (down $16 million), with Q3 (Jul–Sep) sales at 102%. Sanitaryware grew 3% (51% of sales), Washlet 8% (39%), faucets fell 5% (7%); Washlet units grew 2% (3% in Q3). Existing-home sales were 99% for January–June; Washlet demand is firm but distributors are adjusting inventory. Sell-out continues to grow, with an Aurora toilet launch campaign and a 70-million-unit cumulative Washlet shipments message.
Two KPI boxes in US dollars, product growth table on the left, market commentary and marketing photos on the right, conclusion banner
High interest rates keep US home sales stagnant and affect remodel grades, while awareness of bidet seats keeps rising although penetration is still in single digits (versus over 80% in Japanese households). Kitchen and bath shops are adjusting inventory, but sell-out at major dealers is growing double digits and e-commerce and multi-store retail should keep growing, with a new product introduced in FY2026. TOTO is pushing NEOREST-led integrated Washlet toilets via showroom support, online and social advertising, designer events and seminars; the new Morrow plant is running and should add manufacturing profit from the second half.
Flow diagram with environment boxes, arrows into a sell-out box and central blue message, initiatives list with check marks, showroom and factory photos, conclusion banner
Local-currency sales: Taiwan NT$2,969 million (103%), Vietnam 8,143 億 dong (126%), India ₹1,664 million (119%), Thailand 316 million baht (103%). Asia totals ¥276 億円, split Taiwan 54%, Vietnam 18%, India 10%, Thailand 6% and other 12%. Sanitaryware grew 9%, Washlet 28% and faucets 8%, with Washlet units up 30% (97% in Q3). Taiwan Q3 fell to 89% on a showroom closure for renovation, Vietnam Q3 was 161%, Thailand Q3 was 89% after flooding.
Local-currency KPI rows on the left, donut chart of country mix on the right, country commentary and Q3 table bottom-left, product growth table bottom-right, conclusion banner
The renewed Taipei showroom opened on September 16 with TOTO's first overseas public-space operation verification room; visitor groups reached 160% of target and quotation value 144% YoY. TOTO opened a Riyadh Technical Center in Saudi Arabia on September 19, its first in the Middle East, showcasing NEOREST collections to key customers amid many large projects, while operating with attention to the regional situation.
Split layout: Taiwan showroom photos and results on the left, Riyadh technical center photos on the right, red 'first' badges, conclusion banner
Sales €20 million (114%) and operating profit €0.7 million (down €0.3 million), with Q3 sales at 120%. Washlet unit volume indexed at 120 vs 100 a year earlier (Q3: 115%). TOTO is using its London showroom, reopened in May, to target the luxury housing market and support key plumber and retail partners to expand Washlet adoption in the UK; profit fell on strategic hiring and showroom investment.
Two KPI boxes in euros, bar chart of Washlet unit index, text and showroom seminar photos, conclusion banner
Sales 1,255 million yuan (99%) and operating profit 39 million yuan (up 201 million yuan), with Q3 sales at 86% as project demand fell but retail kept growing double digits. Sanitaryware grew 6% (49% of sales), Washlet fell to 92% (27%), faucets 88% (19%); Washlet units 103%. Structural reform since Q1 2025 is shifting the business to retail and remodel, with retail share rising toward roughly 50%; fixed-cost cuts and better mix returned the business to profit.
Two KPI boxes in yuan, product growth table on the left, combined bar and line chart of retail vs project growth and retail ratio by quarter on the right, conclusion banner
Ceramics sales ¥396 億円 (134%) and operating profit ¥182 億円 (up ¥55). Leading-edge semiconductor demand stays strong on AI and data center investment. Electrostatic chucks were broadly on the initial plan in H1 and supply-chain issues were resolved in Q2; AD parts grew on higher volumes and productivity. TOTO plans large capacity expansion and next-generation product investment for long-term growth.
Two KPI boxes, rounded panel with demand statement, product photos with commentary for each product, blue growth statement, conclusion banner
A 2020–2030 roadmap in three stages: logic moving from 5nm to 3nm, around 2nm and below 2nm, and memory from 128 layers to 300–400 and toward 1,000 layers. Past investment includes ¥110 億円 R&D and ¥60 億円 prototype line at Chigasaki, plus ¥118 億円 for Nakatsu building 4 and ¥300 億円 for phased chuck expansion. Planned Stage 3 spending is about ¥90 億円 R&D, about ¥330 億円 to strengthen R&D and mass production, and about ¥600 億円 for next-generation capacity. Sales grew at a 31% CAGR, and the FY2026 mid-term plan was achieved early.
Timeline grid with stage headers and year columns, market trend arrows, investment rows with red dashed box for future spend, bar chart of sales and operating profit, conclusion banner
TOTO plans investment for next-generation mass production of electrostatic chucks and AD parts. Nakatsu plant (Oita) will make AD parts for leading-edge logic, starting construction in 2026 and operating in 2028 (about ¥110 億円). Buzen plant (Fukuoka) will make chucks for advanced NAND and AD parts for logic, starting in 2027 and operating in 2029 (about ¥600 億円). With the Buzen firing building (about ¥40 億円) and Chigasaki R&D building (about ¥170 億円), the three sites total about ¥330 億円, preparing for market growth after 2030.
Two pink panels for each plant with timelines, Gantt-style chart from 2026 to 2031 for production and R&D, conclusion banner
Section divider for corporate topics.
Full-bleed blue background with centred white title
TOTO endorsed the Taskforce on Nature-related Financial Disclosures because its manufacturing depends on water and earth materials. It analysed water dependency, risks and opportunities in sanitaryware production, set targets such as a water reuse rate, and started web disclosures in line with the TNFD framework.
Headline with TNFD logo, two rounded background boxes, three-step process panel (analysis, measures, disclosure) with icons, source URLs, conclusion banner
TOTO's easy-clean warm bathroom floor won the Kids Design Council Chairman's Award, praised for improving child safety against slips and falls, warmth and cushioning while easing cleaning for parents. A cross-section shows an FRP surface sheet, foam urethane cushion layer, insulated floor pan and base frame.
Headline award statement, bordered reasons box, Kids Design Award logo, product photo and layered cross-section diagram, conclusion banner
Section divider introducing the revised full-year plan.
Full-bleed blue background with centred white title
TOTO revised the full-year plan to sales of ¥7,750 億円 (99% of the initial plan) and operating profit of ¥600 億円 (unchanged), aiming for a second consecutive record in sales and operating profit. Japan housing: sales 100% of plan, operating profit +¥15 億円 from the December price revision and extra cost cuts. Overseas housing: sales 96%, operating profit -¥26 億円 on weaker Americas and China markets. New Domain: sales 102%, operating profit +¥15 億円 as the Q1 supply-chain delay was recovered and demand stays strong.
Blue headline banner, large company-level figures, three segment rows with variance figures and diamond bullets
FY2026 revised plan vs FY2025: sales ¥7,750 億円 vs 7,374 (105%), operating profit ¥600 vs 538 (112%, margin 7.7%), ordinary profit ¥580 vs 607 (96%), net profit ¥460 vs 403 (114%). ROA 7.3%, ROE 8.8%, TOTO-style ROIC 8.4% (vs 8.6% initially). FX assumptions for October 2026–March 2027 are ¥155 per dollar, ¥22.5 per yuan and ¥180 per euro.
P/L and ratio table with prior year, revised plan, FX and initial-plan columns, FX assumption matrix below, conclusion banner
Second-half revised plan: sales ¥4,103 億円 vs 3,881 (106%), operating profit ¥348 vs 330 (8.5% margin, ¥22 below the initial H2 plan of ¥370), ordinary profit ¥332 (88%), net profit ¥247 vs 315 (down ¥68). The FX table repeats the quarterly assumptions.
H2 P/L table with YoY, FX and initial-plan columns, FX matrix, conclusion banner
Full-year operating profit from ¥538 億円 to ¥600: sales/mix +131, price revisions +159, cost reduction +105, external procurement -180 (resin and electronic parts), human capital -101, depreciation -20, IT -5, R&D/production -10, sales investment -41, FX +23. The Middle East impact is now -¥60 億円 for the year (H1 -35, H2 -25) vs -70 initially.
Waterfall chart with callout, Middle East impact table top-right, variance-to-initial-plan row, conclusion banner
Full-year sales: Japan housing ¥4,810 億円, overseas housing ¥2,067 (109%), New Domain ¥870 (129%), total ¥7,750. Operating profit: Japan housing ¥145 (66% YoY but ¥15 above initial plan), overseas housing ¥109 (174%, ¥26 below plan), New Domain ¥380 (132%, ¥15 above plan), other -34, total ¥600.
Sales and operating profit segment tables with YoY, FX and initial-plan variance columns, conclusion banner
Full-year sales plan: Americas ¥830 億円 (110%), Asia ¥605 (110%), Europe ¥72 (127%), Mainland China ¥560 (104%), total ¥2,067. Operating profit: Americas ¥30 (down ¥14, ¥20 below plan), Asia ¥90 (¥14 above plan), Europe -10, Mainland China -1 (from -74), total ¥109. The Americas plan reflects weaker markets; China cut its plan but narrows its loss sharply through retail.
Regional sales and operating profit tables with YoY, FX and initial-plan columns, conclusion banner
Section divider for balance sheet, cash flow and shareholder return topics.
Full-bleed blue background with centred white title
TOTO will buy back up to ¥300 億円 of shares (up to 9.5 million shares, 5.8% of shares outstanding excluding treasury stock) from November 1, 2026 to March 31, 2027, and cancel up to 9.4 million shares on April 30, 2027. The FY2026 dividend plan is ¥120 per share (¥60 interim, ¥60 year-end), up ¥10 from ¥110, for a 42.2% payout ratio under a policy of 40%+ payout with progressive or stable dividends.
Two teal-header panels: buyback details on top, dividend table and annual dividend bar chart from 2016 to 2026 below, conclusion banner
Total assets of ¥8,139 億円 (FY2024), ¥8,274 (FY2025) and a planned ¥8,200 (FY2026), with net assets of ¥5,281 planned. The equity ratio stays near 63.7% and D/E at 0.14x against a discipline of at least 50% equity and 0.5x D/E. Investment securities fall from ¥571 to ¥497 as cross-shareholdings are cut; TOTO-style ROIC rises from 4.8% to 6.9% to 8.4% toward a 2030 target of 12% or more. A new financial strategy including the appropriate equity ratio will be announced at the end of April 2027.
Three stacked balance sheet bar pairs, discipline table on the right, ROIC driver table below, red-bordered note, teal callout, conclusion banner
FY2026 revised plan: operating CF +¥779 億円 (vs 712), strategic capex -576, asset and securities sales +84, investing CF -492, free CF +287, financing CF -497 including the ¥300 億円 buyback, net cash change -210, ending cash ¥1,118 億円. Cash on hand falls from 2.2 to 1.7 months of sales after the buyback, against a 1.5-month discipline.
Cash flow table with highlighted rows, teal callouts on cross-shareholding sales and buyback, cash-on-hand discipline table, conclusion banner
Stage 2 (2024–26) operating CF of ¥2,205 億円 plus cross-shareholding sales funds ¥1,515 億円 of strategic investment and shareholder returns, compared with ¥1,572 in Stage 1. FY2026 capex is revised to ¥576 億円 from ¥527: global strategic investment ¥242 (Washlet products, US sanitaryware plant), ceramics ¥102 (production and development capacity), Japan ¥57 (smart factory), infrastructure ¥175 (systems).
Cash creation vs allocation bar comparison top-left, capital allocation policy boxes top-right, investment table below, conclusion banner
Section divider introducing reference pages.
Full-bleed blue background with centred white title
Japan H1 sales: sanitaryware ¥509 億円 (102%), Washlet ¥550 (104%), faucets ¥420 (99.5%), bathrooms ¥459 (85%), kitchen and vanity ¥221 (97%), other ¥73, total ¥2,231 (98%). Overseas: sanitaryware ¥472 (108%), Washlet ¥364 (122%), faucets ¥159 (104%), other combined ¥23, total ¥1,018 (112%).
Single wide table split into Japan and overseas column groups with prior year, current year and YoY
For 3D NAND, electrostatic chucks offer high material purity for durability, precise surface finishing for wafer temperature control and proprietary bonding for cryogenic performance. For logic, AD parts deliver industry-leading low particle levels and chucks offer uniform heater control. Smart-factory production kept operating margins at 30% even in the FY2023 downturn. Growth drivers are higher unit prices, new-tool and installed-chamber demand, and replacement demand.
Matrix table with rows for technology trends, TOTO strengths and growth drivers, columns for NAND and logic, highlighted summary strip, conclusion banner
Forward-looking statement disclaimer noting that the presentation reflects assumptions as of October 30, 2026 and that actual results may differ materially due to economic, competitive and FX risks, with the TOTO logo and tagline.
White page with disclaimer text at top and centred logo
คำถามทั่วไปเกี่ยวกับสไลด์นี้และเนื้อหาการนำเสนอพื้นฐาน
It is TOTO Ltd.'s 40-page results deck for the first half (April–September 2026) of the fiscal year ending March 2027, published October 30, 2026. It covers H1 results, segment and regional performance, the revised full-year plan, the ceramics investment plan, ESG topics and shareholder returns.
Yes. The original is the Japanese-language 決算説明資料 titled 2027年3月期 第2四半期 決算説明資料, disclosed on TDnet, the Tokyo Stock Exchange's timely disclosure system. The page-by-page summaries on this page are written in English, with yen amounts kept in the company's ¥100 million (億円) unit.
Net sales were ¥364.7 billion (¥3,647 億円, +4%), operating profit ¥25.2 billion (¥252 億円, +21%) with a 6.9% margin, and net profit attributable to owners ¥21.3 billion (¥213 億円, 2.4x the prior year). Sales and net profit were first-half records.
The New Domain ceramics business makes electrostatic chucks and AD parts for semiconductor etching equipment. In FY2025 it was about 9% of sales but 51% of operating profit, and in H1 it earned ¥182 億円 of the group's ¥252 億円 operating profit. The deck outlines about ¥330 億円 of near-term and about ¥600 億円 of next-generation capacity investment.
Sales of ¥775 billion (¥7,750 億円, 99% of the initial plan) and operating profit of ¥60 billion (¥600 億円, unchanged), with net profit of ¥460 億円. Japan housing and ceramics were raised by ¥15 億円 each while overseas housing was cut by ¥26 億円.
A share buyback of up to ¥30 billion (up to 9.5 million shares) running November 1, 2026 to March 31, 2027, with cancellation planned for April 30, 2027, and a planned annual dividend of ¥120 per share, up ¥10, for a 42.2% payout ratio.
Japan housing and ceramics report April–September 2026, while overseas subsidiaries report January–June 2026 (India uses April–September). The deck notes these periods on its segment pages and FX tables.
Yes. It is a good model for half-year results decks: a highlights page, P/L table with FX-adjusted variance, operating-profit waterfall, segment and regional pages with one-line conclusion banners, a revised guidance section and a capital allocation section. You can download the PDF from this page.

Create Your Own Slides
Turn your ideas into professional presentations in seconds with 2slides AI.
อ้างอิงการออกแบบมืออาชีพ เลือกสไตล์ของคุณ และสร้างสไลด์ด้วยการแสดงผลข้อความที่สมบูรณ์แบบ ขับเคลื่อนโดย Nano Banana—เริ่มสร้างการนำเสนอของคุณตอนนี้
เอเจนต์ AI ของคุณสำหรับสไลด์ ประหยัดเวลา เปล่งประกายเร็วขึ้นด้วยการสร้างงานนำเสนออัจฉริยะ




© 2026 2slides สงวนลิขสิทธิ์