
Kuulub kogumikku Investoresitluste näited · Jaapani investoriesitluste näited
Oji Holdings (TSE: 3861), Japan's largest paper and pulp group, presents its H1 FY2026 results (April-September 2026) and a revised full-year outlook. This is a Japanese-language deck (2026年度第2四半期決算説明会資料) published on TDnet, the Tokyo Stock Exchange's timely disclosure system, on November 6, 2026; all analysis on this page is in English with yen figures kept in the company's own units (億円 = ¥100 million). FY2026 runs from April 2026 to March 2027. Net sales rose to ¥958.0 billion (9,580億円, +430), operating profit slipped to 155億円 (-12) and interim net profit rose to 117億円 (+8). The full-year operating profit forecast was cut from 600億円 to 450億円 because of the prolonged Middle East situation and a slow pulp-market recovery, while net profit guidance of 350億円 and the ¥36 per-share dividend were kept.
Kasutab selle esitluse kaanepilti stiilieeskujuna slaididele, mis luuakse sinu enda sisust. Või vali allpool mõni leht ja kasuta selle paigutust eeskujuna.
Kiirnavigatsioon
Sildid
Jaga slaide
Oji Holdings (TSE: 3861), Japan's largest paper and pulp group, presents its H1 FY2026 results (April-September 2026) and a revised full-year outlook. This is a Japanese-language deck (2026年度第2四半期決算説明会資料) published on TDnet, the Tokyo Stock Exchange's timely disclosure system, on November 6, 2026; all analysis on this page is in English with yen figures kept in the company's own units (億円 = ¥100 million). FY2026 runs from April 2026 to March 2027. Net sales rose to ¥958.0 billion (9,580億円, +430), operating profit slipped to 155億円 (-12) and interim net profit rose to 117億円 (+8). The full-year operating profit forecast was cut from 600億円 to 450億円 because of the prolonged Middle East situation and a slow pulp-market recovery, while net profit guidance of 350億円 and the ¥36 per-share dividend were kept.
Iga slaidilehe üksikasjalik vaade, sealhulgas paigutus, põhisisu ja visuaalsed elemendid.
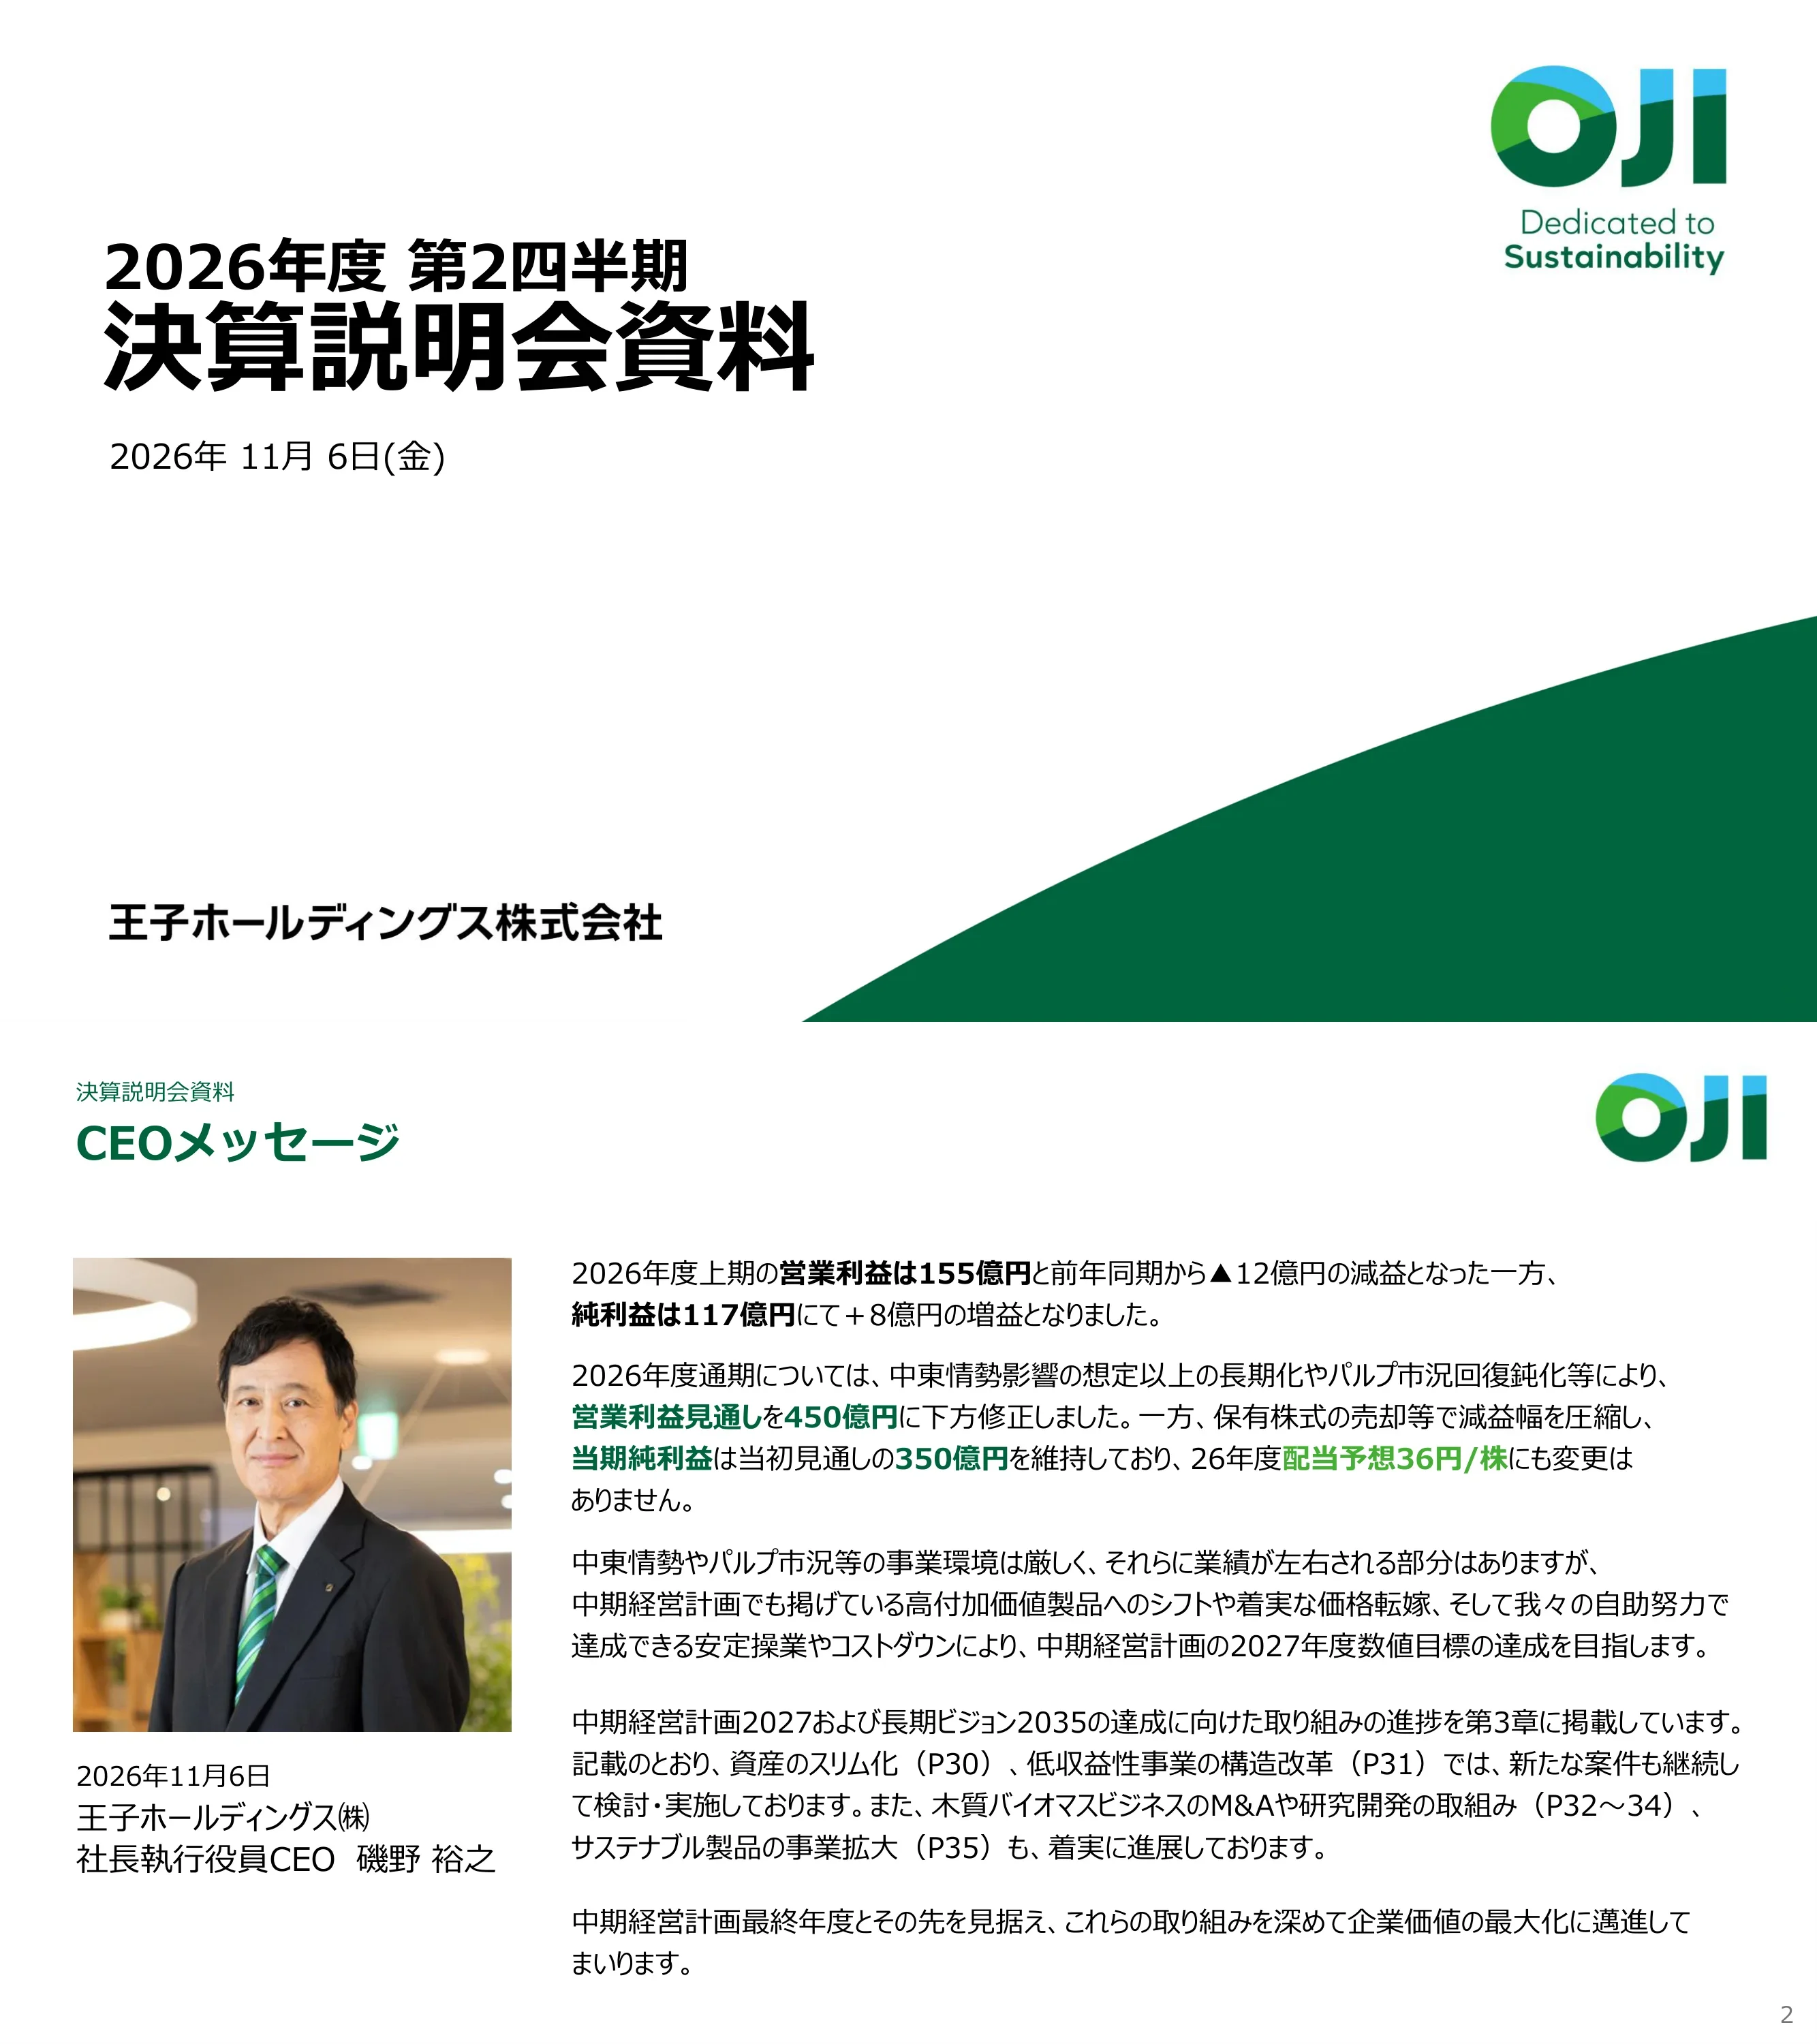
Title page reading 2026年度 第2四半期 決算説明会資料 (FY2026 Second-Quarter Earnings Presentation Materials), dated Friday, November 6, 2026, from Oji Holdings Corporation (王子ホールディングス株式会社). The OJI logo with the tagline 'Dedicated to Sustainability' sits top right.
White cover with large left-aligned bold Japanese title, date beneath, company name at bottom left and a sweeping dark-green curve in the lower-right corner.
President and CEO Hiroyuki Isono summarises the half: H1 FY2026 operating profit was 155億円, down 12億円 year on year, while net profit was 117億円, up 8億円. Because the Middle East situation has lasted longer than assumed and the pulp market recovery has been slower, the full-year operating profit forecast was revised down to 450億円. Gains on sales of shareholdings offset part of the decline, so the net profit forecast of 350億円 and the 36円 per share dividend forecast are unchanged. The CEO says high-value-added products, steady price pass-through, stable operations and cost cuts are aimed at reaching the medium-term plan's FY2027 targets, and points to progress on asset slimming (p.30), restructuring of low-profit businesses (p.31), wood-biomass M&A and R&D (pp.32-34) and sustainable products (p.35).
Portrait photo of the CEO on the left with date, company and name caption; four paragraphs of message text on the right with key figures highlighted in bold green.
Three blocks. 01 H1 FY2026 results: consolidated operating profit 155億円 (down 12億円 year on year) and interim net profit 117億円 (up 8億円). Price revisions and production restructuring helped, but soaring raw-material prices from the Middle East situation and higher logistics and labour costs weighed on operating profit; FX gains from revaluing foreign-currency receivables and payables lifted net profit. 02 FY2026 forecast: operating profit 450億円 (150億円 below the original forecast), net profit 350億円 (unchanged), ROE 3.2% (down 0.1pt). 03 Medium-term plan 2027 follow-up: dividend of 36円 per share maintained; the cumulative buyback target of 1,000億円 for FY2026 was reached in May, and the 1,500億円 cumulative target through FY2027 is maintained.
Two side-by-side summary tables (H1 actuals vs prior year; FY forecast vs original forecast) with bullet explanations, plus a full-width green band for the medium-term plan follow-up.
Four chapters: 01 H1 FY2026 results (consolidated overview p.7, segment sales and operating profit p.10, segment profit analysis for Household & Industrial Materials p.11, Functional Materials p.12, Forest Resources & Environment Marketing p.13, Printing & Communications Media p.14); 02 FY2026 forecast (consolidated forecast p.16, segment forecast p.19, segment profit changes p.20, external-environment sensitivities p.21, comparison with original forecast p.22); 03 Medium-term plan 2027 follow-up (FY2026-27 outlook p.28, shareholder returns p.29, asset slimming p.30, restructuring of low-profit businesses p.31, wood biomass p.32, sustainable products p.35, circular economy p.36, external ESG ratings p.37); 04 Appendix (segment sales trend and more, p.39).
Three columns of numbered chapter headers with light-green striped rows listing topics and page numbers; appendix block at bottom right.
Legal notice stating that the material is not a disclosure document under the Financial Instruments and Exchange Act and does not guarantee accuracy or completeness; forecasts are based on information available at the time of the briefing and contain uncertainties; investors should not rely solely on this material for investment decisions, and the company accepts no liability for any damage arising from its use.
Single block of centred body text on a plain white page with the logo top right.
Chapter divider introducing the first section, the summary of FY2026 second-quarter (first-half) results.
Large white '01' on a dark-green vertical panel on the left with the section title in green on the right.
In 億円, H1 FY2025 vs H1 FY2026: net sales 9,150 to 9,580 (+430); operating profit 167 to 155 (-12), of which domestic companies 181 to 199 (+18) and overseas companies -14 to -44 (-30); ordinary profit 88 to 115 (+27); interim net profit attributable to owners 109 to 117 (+8); depreciation 441 to 468 (+27). The average exchange rate moved from 146.0 to 159.5 yen per US dollar. Consolidated subsidiaries: 94 domestic (unchanged) and 120 overseas (down 2 from 122), for 214 in total. Overseas changes include additions in Vietnam packaging (+1), Austrian biorefinery (+3), overseas plantation (+1) and Europe (+1), and removals in Malaysian printing (-1) and Australian packaging (-7). Equity-method affiliates rose by one net.
Three-column financial table (prior year, current year highlighted green, change) with a footnote box explaining changes in the scope of consolidation.
Domestic companies' operating profit rose from 181億円 to 199億円 (+18). Price effect +260億円 (paper +245, pulp +15); volume -35億円; raw-material and fuel prices -150億円 (chips -65, purchased pulp and base paper -25, chemicals -25, power and gas -15; Middle East impact -80; FX effect -53); cost and other -57億円 (logistics and labour -35, corporate companies -15, other inflation). By segment: Household & Industrial Materials +42, Functional Materials +19, Forest Resources & Environment Marketing -4, Printing & Communications Media -26, Other -13.
Waterfall chart from the grey prior-year bar to the green current-year bar with callout boxes for each driver and a segment-by-driver table beneath.
Overseas companies' operating loss widened from -14億円 to -44億円 (-30). Price effect -5億円 (paper -5, pulp -10, wood +10); volume +25億円 (paper +15, pulp +10); raw-material and fuel prices -10億円 (Middle East impact -40 and others); cost and other -40億円 (FX -40 and others). By segment: Household & Industrial Materials +66, Functional Materials +10, Forest Resources & Environment Marketing -42, Printing & Communications Media -25, Other -39.
Downward waterfall from the prior-year loss bar to the current-year loss bar with callouts and a segment-by-driver table.
In 億円 (sales / operating profit): Household & Industrial Materials 4,620 / 52 to 4,788 / 160 (+168 / +108); Functional Materials 1,155 / 54 to 1,189 / 83 (+33 / +29); Forest Resources & Environment Marketing 1,909 / 53 to 2,070 / 7 (+161 / -46); Printing & Communications Media 1,362 / 35 to 1,317 / -16 (-45 / -51); Other 104 / -27 to 216 / -79 (+112 / -52); consolidated 9,150 / 167 to 9,580 / 155 (+430 / -12). Notes: sales include inter-segment sales; Other includes adjustments.
Colour-coded segment rows (orange, teal, green, blue, grey) against three pairs of sales/profit columns.
Headline: domestic profit rose on price revisions despite higher costs, and overseas profit rose on restructuring effects. Operating profit +108億円, from 52億円 (domestic 94, overseas -42) on sales of 4,620億円 to 160億円 (domestic 136, overseas 24) on sales of 4,788億円. Domestic +42億円: sales and market factors +140, raw-material and fuel prices -70 (Middle East -25). Overseas +66億円: sales and market +45, other cost factors +36. Domestic containerboard: 1,419 to 1,393 thousand tonnes (98.2%), unit price 85.34 to 88.15 円/kg, sales 1,211 to 1,228億円. Corrugated boxes: 1,499 to 1,482 million m2 (98.9%), 78.55 to 81.93 円/m2, sales 1,177 to 1,214億円. Charts show Nikkei domestic market prices for coated white board, C-liner, corrugated sheet and tissue (right axis, 円/5-box pack) since April 2021, and Australian Newcastle FOB coal prices.
Left KPI stack (big +108 figure, current vs prior period), centre driver panel, two line charts, and a product volume/price table across the bottom.
Headline: domestic profit rose on price revisions and overseas profit rose on cost reductions. Operating profit +29億円, from 54億円 (domestic 51, overseas 3) on sales of 1,155億円 to 83億円 (domestic 70, overseas 13) on sales of 1,189億円. Domestic +19億円: sales and market +45, raw-material and fuel prices -25. Overseas +10億円: other cost factors +10. Thermal paper (domestic plus overseas): volume 2,027 to 1,842 million m2 (90.9%), unit price 22.54 to 24.36 円/m2, sales 457 to 449億円. Charts track Dubai crude ($/bbl) and domestic naphtha (thousand 円/kl) since April 2021, showing a sharp spike in 2026, and first/second-half thermal paper volumes from FY2021 to FY2026.
Teal-themed version of the segment dashboard: KPI stack, driver panel, crude/naphtha line chart, stacked half-year bar chart and product table.
Headline: profit fell on costs from FX and extended maintenance shutdowns. Operating profit -46億円, from 53億円 (domestic 33, overseas 20) on sales of 1,909億円 to 7億円 (domestic 29, overseas -22) on sales of 2,070億円. Overseas -42億円: other cost factors -47 (FX and extended shutdowns), sales and market +10. Pulp price assumptions: NBKP 710 $/t in calendar 2025 to 655 $/t assumed for calendar 2026 (-55), with 660 actual for January-June, 650 assumed for July-December and 660 in October; LBKP 540 to 590 $/t (+50), with 590, 585 and 605 respectively. Market pulp sales: 1,139 to 1,241 thousand tonnes (108.9%), 86.13 to 98.73 円/kg, 981 to 1,225億円 (+244). Power sales (domestic): 857 to 850 GWh. Chart shows China net prices for Chilean NBKP and Brazilian LBKP since April 2021.
Green-themed dashboard with KPI stack, NBKP/LBKP price-pill timelines, pulp price line chart and pulp/power sales table.
Headline: domestic profit fell as costs outpaced price revisions, and overseas profit fell on weaker markets. Operating profit -51億円, from 35億円 (domestic 24, overseas 11) on sales of 1,362億円 to -16億円 (domestic -2, overseas -14) on sales of 1,317億円. Domestic -26億円: raw-material and fuel prices -55, sales and market +40. Overseas -25億円: sales and market -25. Domestic newsprint and printing/communication paper: 746 to 669 thousand tonnes (89.7%), 127.80 to 135.22 円/kg, sales 953 to 905億円 (-48). Charts show Nikkei prices for A2 and A3 coated paper stepping up sharply in 2026 and chip prices ($/t) for Australian hardwood, US softwood and Thai hardwood.
Blue-themed dashboard with KPI stack, driver panel, two step/line charts and a product table.
Chapter divider for the full-year FY2026 forecast section.
Large white '02' on a dark-green vertical panel with the section title on the right.
In 億円, FY2025 actual vs FY2026 forecast: net sales 18,617 to 19,600 (+983); operating profit 346 to 450 (+104), of which domestic 399 to 440 (+41) and overseas -53 to 10 (+63); ordinary profit 405 to 300 (-105); net profit 556 to 350 (-206); ROE 5.0% to 3.2% (-1.8pt); depreciation 928 to 921 (-7); average FX 150.7 to 159.7 yen per dollar. Assumptions for H2: 160円/US$, chips on current contracts plus Middle East impact, recovered paper flat, Australian thermal coal 145 $/t, Dubai crude 113 $/bbl. Annual operating profit sensitivities: 1% move in the yen against the dollar about ±6.6億円 (stronger dollar negative), Brazilian real ±6.5億円, NZ dollar ±6.1億円, euro ±1.2億円 (stronger dollar positive); pulp ±3.6億円 per $1/t; chips ±4.8億円 per $1/t; recovered paper ±33.8億円 per 1円/kg; coal ±1.0億円 per $1/t; Dubai crude ±2.9億円 per $1/bbl.
Forecast table with green forecast column at top; dense two-part footnote area listing assumptions and sensitivities.
Domestic operating profit is forecast to rise from 399億円 to 440億円 (+41). Price effect +590億円 (paper +555, pulp +35); volume -15億円; raw-material and fuel prices -455億円 (chips -125, purchased pulp/base paper -80, chemicals -70, recovered paper -60; Middle East impact -230; FX -95); cost and other -79億円 (logistics and labour -70, other inflation). By segment: Household & Industrial Materials +35, Functional Materials +17, Forest Resources & Environment Marketing -8, Printing & Communications Media -7, Other +4.
Waterfall chart with callouts and a segment-by-driver table under the bridge.
Overseas operating profit is forecast to swing from -53億円 to +10億円 (+63). Price effect +245億円 (paper +110, pulp +95, wood +40); volume +35億円 (paper +20, pulp +15); raw-material and fuel prices -150億円 (Middle East impact -190 and others); cost and other -67億円 (FX -60 and others). By segment: Household & Industrial Materials +98, Functional Materials +35, Forest Resources & Environment Marketing +61, Printing & Communications Media -48, Other -83.
Upward waterfall from a negative starting bar to a small positive ending bar, with driver callouts and segment matrix.
In 億円, FY2025 actual vs FY2026 forecast (sales / operating profit): Household & Industrial Materials 9,433 / 197 to 9,680 / 330 (+247 / +133); Functional Materials 2,360 / 108 to 2,400 / 160 (+40 / +52); Forest Resources & Environment Marketing 3,897 / 67 to 4,350 / 120 (+453 / +53); Printing & Communications Media 2,721 / 75 to 2,740 / 20 (+19 / -55); Other 207 / -101 to 430 / -180 (+224 / -79); consolidated 18,617 / 346 to 19,600 / 450 (+983 / +104).
Colour-coded segment table with prior, forecast (green) and change column pairs.
Household & Industrial Materials: operating profit 197 to 330億円 (+133; domestic 255 to 290, +35; overseas -58 to 40, +98), margin 2.1% to 3.4%. Functional Materials: 108 to 160億円 (+52; domestic 108 to 125, +17; overseas 0 to 35, +35), margin 4.6% to 6.6%. Forest Resources & Environment Marketing: 67 to 120億円 (+53; domestic 73 to 65, -8; overseas -6 to 55, +61), margin 1.7% to 2.8%. Printing & Communications Media: 75 to 20億円 (-55; domestic 62 to 55, -7; overseas 13 to -35, -48), margin 2.8% to 0.7%.
Four horizontal colour bands, each with a mini table (sales, operating profit, domestic, overseas, margin) and an arrow-shaped callout with the profit change and domestic/overseas split.
Annual operating profit impact (億円) of a 10% stronger US dollar, by currency at the H2 assumed rates: yen at 160.00/USD -66 (hurts Household & Industrial, Functional and Printing; includes translation of dollar-denominated profit); Brazilian real at 5.30/USD +65 and NZ dollar at 1.75/USD +61 (both benefit Forest Resources & Environment Marketing); euro at 0.89/USD +12 (Other). Price sensitivities: pulp sales/purchases +$10/t adds 36億円 (positive for Forest Resources, negative for the other paper segments); Dubai crude +$10/bbl (heavy oil, bunker oil and others) reduces profit by 29億円.
Matrix with currencies and commodities as rows and segments as coloured columns; chevron arrows show direction and strength of each impact, with totals on the right.
In 億円, original vs revised FY2026 forecast: net sales 19,400 to 19,600 (+200); operating profit 600 to 450 (-150), of which domestic 480 to 440 (-40) and overseas 120 to 10 (-110); ordinary profit 450 to 300 (-150); net profit 350 to 350 (unchanged); ROE 3.3% to 3.2% (-0.1pt); depreciation 891 to 921 (+30); average FX 155.0 to 159.7 yen per dollar (+4.7).
Three-column comparison table (original, revised in green, change).
Domestic forecast cut from 480億円 to 440億円 (-40). Price effect +90億円 (paper +70, pulp +20); volume -10億円; raw-material and fuel prices -175億円 (chips -65, chemicals -65, recovered paper -50; worsening Middle East impact -125); cost and other +55億円 (corporate companies +20, group head-office costs +20, other cost reductions). By segment: Household & Industrial Materials -91, Functional Materials +33, Forest Resources & Environment Marketing -8, Printing & Communications Media -18, Other +44.
Waterfall between the original and revised forecast bars with callouts and a segment table.
Overseas forecast cut from 120億円 to 10億円 (-110). Price effect -15億円 (paper -5, pulp -35, wood +25); volume -30億円 (paper -20, pulp -10); raw-material and fuel prices -20億円 (worsening Middle East impact -65 and others); cost and other -45億円 (FX -20, efficiency and other -25). By segment: Household & Industrial Materials +26, Functional Materials -3, Forest Resources & Environment Marketing -62, Printing & Communications Media -52, Other -19.
Descending waterfall from a tall grey bar to a small green bar with callouts and segment table.
Second-half comparison. Domestic H2 operating profit cut from 330億円 to 241億円 (-89): price +75, volume -5, raw materials -165, cost and other +6; by segment Household & Industrial -77, Functional +5, Forest Resources -3, Printing -24, Other +10. Overseas H2 cut from 150億円 to 54億円 (-96): price -5, volume -30, raw materials -50, cost and other -11; by segment Household & Industrial +2, Functional -3, Forest Resources -54, Printing -35, Other -6.
Two stacked mini-bridges (domestic and overseas), each with a grey original bar, a driver table and a green revised bar.
In 億円, original vs revised forecast (sales / operating profit): Household & Industrial Materials 9,710 / 395 to 9,680 / 330 (-30 / -65); Functional Materials 2,370 / 130 to 2,400 / 160 (+30 / +30); Forest Resources & Environment Marketing 4,210 / 190 to 4,350 / 120 (+140 / -70); Printing & Communications Media 2,740 / 90 to 2,740 / 20 (0 / -70); Other 370 / -205 to 430 / -180 (+60 / +25); consolidated 19,400 / 600 to 19,600 / 450 (+200 / -150).
Segment table with original, revised (green) and change column pairs.
Chapter divider for the progress update on the Medium-Term Management Plan 2027.
Large white '03' on a dark-green panel with the section title on the right.
FY2026 operating profit is planned to rise from 155億円 in H1 (actual) to 295億円 in H2 (+140), for 450億円 for the year. Main H2 drivers: domestic: timing of shutdowns +50 (more shutdown days in H1), Middle East cost increase -70, other raw-material prices -50 (purchased pulp and recovered paper), price increases +125 (including Middle East-related increases); overseas: shutdown timing +50, pulp prices +15 (autumn demand), volume +40 (more operating days and expansion). FY2027 medium-term plan targets are maintained: ROE 8%, operating profit 1,200億円, net profit 800億円. Despite a tough environment including the prolonged Middle East situation, the company will pursue price pass-through, stable operations and cost cuts to hit the plan's profit targets.
Left: two-bar column chart (H1 vs H2) with a circular full-year badge and a driver table. Right: target table with three KPIs and a commentary paragraph.
Dividend forecast unchanged from the original plan. Medium-term plan policy: payout ratio 50%, dividend floor 24円 per share per year; FY2026 dividend forecast 36円 per share. Cumulative share buybacks: 293億円 by FY2024, 770億円 by FY2025 (293 + 477), and the FY2026 cumulative target of 1,000億円 achieved (770 + 230) in H1, with shares cancelled in May. The FY2027 target is 1,500億円 cumulative for FY2024-FY2027, with the remaining 500億円 to be executed steadily.
Left: dividend policy table. Right: stacked column chart of cumulative buybacks with an 'achieved' badge and dotted target bar.
Cross-shareholding reduction. Policy shareholdings total 1,100億円, of which 830億円 sold so far (290 in FY2024, 410 in FY2025, 130 in H1 FY2026), with 270億円 more planned through FY2030 (170 plus 100 newly added). Retirement-benefit trust shares total 400億円, of which 290億円 sold (140 in FY2024, 150 in FY2025), with 110億円 planned through FY2027 (60 plus 50 added). Planned total 1,500億円, completed 1,120億円. The reduction target through FY2030 was raised from 1,200億円 to 1,500億円 (+300). Real estate: idle land inside a plant in the Kansai region was sold, producing an extraordinary gain of 30億円, and other properties are under review. Proceeds will fund growth businesses and appropriate shareholder returns.
Two stacked bar columns (policy shareholdings and retirement-benefit trust shares) feeding a total box; right side shows two progress panels.
The group continues to review and exit low-profit businesses. FY2025 actions: Oceania reorganisation (exit from New Zealand containerboard, sale of Australian corrugated business); domestic tissue and adult diaper restructuring (closure of Oji Nepia's Tomakomai, Edogawa and Fujinomiya plants); domestic newsprint restructuring (Oji Paper Tomakomai N4 machine stopped); domestic corrugated restructuring (some corrugators in Shikoku stopped). FY2026 actions: sale of the Malaysian printing and delivery services business; European packaging restructuring (Walki's Garstang plant in the UK closed); domestic sawmill restructuring (consolidation from five plants to three); consolidation of corrugated production sites in southern Malaysia; closure of the New Zealand board converting plant (OjiFS Hamilton); sale of the Myanmar corrugated business. Nine further restructuring plans are under review (excluding those listed and small businesses; not limited to exits).
Grey band with four FY2025 action tiles above a dark-green band with six FY2026 tiles; bold count of additional plans at the bottom.
Maximising the value of forest resources by moving into next-generation materials, chemicals and energy from wood's three components. Cellulose: high-purity cellulose for apparel fibres (Yonago, AustroCel), cellulose nanofiber as a light high-strength material (Innovation Promotion Division), microcrystalline cellulose for pharmaceutical excipients and cosmetics (Chemfield, Nordic Bioproducts Group investment). Cellulose and hemicellulose: sugar solution and bioethanol as low-carbon fuels and bio-feedstock (Yonago demonstration since 2025, AustroCel in commercial operation) and biomass resist for advanced semiconductor manufacturing (commercialisation from 2028). Hemicellulose: sulfated hemicellulose for veterinary and human medicines (Oji Pharma). Lignin: lignin-derived high-function products (in development) and hydrogel for agricultural soil water retention (AustroCel). All three: biomethanol (demonstration from FY2027), biochar for agriculture and industry (demonstration from FY2026), biocarbon as a fossil-fuel substitute for steel (production from FY2029 with Brazil's Bionow).
Forest photo column on the left with arrows into five product clusters, each with product photos, uses and status tags.
Oji brings in technology through acquisitions and investments to expand high-value functional cellulose globally, linking AustroCel (Austria), Oji Paper's Yonago mill (Japan), Chemfield (India) and Nordic Bioproducts Group (Finland) to share know-how and build an integrated global production system. Products range from general dissolving pulp (for rayon) to specialty dissolving pulp with higher purity or viscosity, used for acetate (cigarette and water filters, LCD film), ethers (stabilisers, thickeners), microcrystalline cellulose for tablet excipients (Chemfield sells DP-derived MCC; NBG is developing a novel MCC process) and other uses such as sausage casings and tyre cord. Sales target for 2030: 500億円 or more for specialty DP and downstream businesses, with further growth from M&A and new applications.
Country flag list at top left, bullet strategy statements, then a horizontal application map with line icons and a circular 2030 target badge.
Accelerating R&D and commercialisation in bio-manufacturing, semiconductors and healthcare. Wood-derived pharmaceuticals (sulfated hemicellulose): veterinary API approval obtained in Australia and clinical research on rare animals under way in Japan; for human use, a Phase I trial is running, targeting launch in the 2030s as a heparin alternative. Sales targets 100億円+ in 2030 and 500億円+ in 2035 (including non-wood medicines). Biomass resist: joint development with imec achieved 10 nm line patterns on a next-generation EUV tool and pattern transfer by etching; commercialisation targeted for 2028; targets 30億円+ in 2030 and 300億円+ in 2035. Wood sugar and ethanol: samples provided to more than 20 users, and collaboration in fuels and chemicals under study; targets 5億円+ in 2030 and 300億円+ in 2035.
Three rows, each with a product photo, a 2025-2035 chevron timeline, a 2026 topics text block and paired circular 2030/2035 sales targets.
Packaging regulation is treated as a business opportunity: the EU Packaging and Packaging Waste Regulation (PPWR) applies generally from August 2026 and India has enforced plastic-waste rules, so demand for compliant paper and board is expected to grow. A bar chart shows sustainable-product sales (億円) rising from roughly 700 in FY2024 to roughly 1,100 in FY2025, around 1,200 planned for FY2026-27, about 1,750 in the 2030 plan and about 2,400 in the 2035 plan (bar labels not printed; values read from the axis), with pie charts of the 2026 and 2030 mix (liquid cartons and cup stock, food and industrial plastic-free packaging, phenol-free thermal paper, building materials, PLA and mono-material plastics). OJI4U is a total packaging solution in Southeast Asia combining Walki abrasion-resistant and barrier papers; an example replaces expanded polystyrene cushioning with a hybrid paper cushion of Walki liner plus GSPP corrugated sheet (Malaysia).
Left: bar chart with two donut charts and legend. Right: background box, OJI4U logo panel and a product example box with an illustration.
Oji's Renewa resource-circulation solution turns hard-to-recycle materials (paper cups, aluminium-lined cartons, paper hand towels, PE-laminated kraft bags) into recycled products such as corrugated boxes, tissue boxes, paper towels and paper-yarn textiles. About 30 partner companies participate across offices, factories, sports and tourism venues, shops and hotels. Recent cases: Ito En (PE-coated kraft bag recycling), Kawasaki Frontale (paper cup recycling), Kagome (aluminium-lined carton recycling) and Daio Wasabi Farm (horizontal recycling of paper hand towels). Awards: Good Design Award 2026, the 50th Kinoshita Prize new-creation category, and Japan Packaging Contest 2026 awards for the Kagome project.
Top flow from difficult materials to recycled products; central network map of partner logos and a Japan map; right column of awards.
MSCI ESG rating raised to AA (August 2026), two notches up from BBB. CDP A List (February 2026): Forests for the fourth consecutive year and Water Security for the second. World Benchmarking Alliance: 4th of 750 companies in the Nature sector and named a top performer (January 2026). Nature Action 100: scored on 26 of 50 items, third among 100 companies (October 2026).
Three columns (MSCI, CDP, other bodies), each with a green header, a headline result, logo badges and a note box.
Chapter divider for the reference materials.
Large white '04' on a dark-green panel with the title 参考資料 (Appendix).
Consolidated net sales (億円): FY2019 15,076; FY2020 13,590; FY2021 14,702; FY2022 17,066; FY2023 16,963; FY2024 18,493; FY2025 18,617; FY2026 forecast 19,600. Household & Industrial Materials grew from 6,861 to 9,680; Functional Materials 2,147 to 2,400; Forest Resources & Environment Marketing 2,856 to 4,350; Printing & Communications Media 2,927 to 2,740. Overseas sales ratio rose from 29.9% (FY2019) to 41.9% (FY2025) and 41.3% forecast for FY2026. Note: from FY2025 Walki and IPI moved from Other to Household & Industrial Materials, and FY2023-FY2024 have been restated.
Stacked column chart by segment with a line for overseas sales ratio; red-bordered note box about the segment change.
Operating profit (億円, domestic / overseas) and net profit: FY2019 1,061 (700 / 361), net 582, margin 7.0%; FY2020 848 (632 / 216), net 496, 6.2%; FY2021 1,201 (615 / 586), net 875, 8.2%; FY2022 848 (188 / 660), net 565, 5.0%; FY2023 726 (648 / 78), net 508, 4.3%; FY2024 677 (476 / 201), net 462, 3.7%; FY2025 346 (399 / -53), net 556, 1.9%; FY2026 forecast 450 (440 / 10), net 350, 2.3%.
Paired columns per year (stacked operating profit and net profit) with an orange operating-margin line.
Book value per share / EPS (円) and ROE: FY2019 699.12 / 58.78 / 8.5%; FY2020 758.28 / 50.13 / 6.9%; FY2021 859.29 / 88.35 / 10.9%; FY2022 945.27 / 57.00 / 6.3%; FY2023 1,083.13 / 51.31 / 5.1%; FY2024 1,177.99 / 47.34 / 4.3%; FY2025 1,257.44 / 61.10 / 5.0%; FY2026 forecast 1,256.53 / 40.94 / 3.2%.
Paired column chart (BPS and EPS) with an orange ROE line.
Net interest-bearing debt (億円) and D/E ratio (net debt / net assets): March 2020 4,973 (0.6x); March 2021 5,114 (0.6x); March 2022 5,947 (0.7x); March 2023 7,313 (0.8x); March 2024 6,739 (0.6x); March 2025 8,375 (0.7x); March 2026 8,809 (0.8x); March 2027 forecast 9,476 (0.9x).
Single-series column chart with an orange D/E ratio line.
Capital expenditure and investment (億円, domestic / overseas) vs depreciation (domestic / overseas): FY2019 1,067 (547 / 519) vs 634 (381 / 253); FY2020 1,230 (441 / 789) vs 628; FY2021 2,228 (478 / 1,750) vs 659; FY2022 1,326 (448 / 878) vs 730; FY2023 1,333 (348 / 985) vs 795; FY2024 2,204 (503 / 1,702) vs 892 (391 / 501); FY2025 1,352 (488 / 863) vs 928 (397 / 531); FY2026 forecast 1,454 (562 / 892) vs 921 (382 / 539).
Paired stacked columns per year: green for investment, blue for depreciation.
Consolidated employees (domestic / overseas): March 2020 36,810 (16,987 / 19,823); March 2021 36,034 (16,578 / 19,456); March 2022 35,608 (16,368 / 19,240); March 2023 37,845 (16,192 / 21,653); March 2024 38,322 (16,283 / 22,039); March 2025 39,136 (16,233 / 22,903); March 2026 38,757 (16,264 / 22,493).
Stacked column chart with domestic (dark green) and overseas (light green) segments.
Japan paper and board demand for April-September 2026 (thousand tonnes, year-on-year): paperboard domestic shipments 5,265 (99.4%), imports 100 (85.0%), total 5,365 (99.0%), including containerboard 4,300 (99.8%) and folding boxboard 691 (97.0%). Paper domestic shipments 4,152 (95.8%), imports 441 (106.3%), total 4,593 (96.7%): tissue 907 (99.6%; imports 151 including converted products), packaging paper 292 (99.2%), newsprint 618 (90.8%), printing and communication paper 2,057 (94.5%; imports 273), miscellaneous 279 (102.6%). Grand total domestic 9,417 (97.8%), imports 541 (101.6%), total 9,958 (98.0%). Corrugated board production 7,025 million m2 (99.7%). Sources: Japan Paper Association, Ministry of Finance trade statistics and the corrugated industry federation; import data are preliminary.
Industry statistics table split into paperboard and paper blocks, with a separate corrugated row and source footnotes.
Closing slide with the OJI logo and the tagline 'Dedicated to Sustainability'.
Centred logo on a plain white background.
Levinud küsimused selle slaidi ja esitluse sisu kohta.
The original is a Japanese-language earnings presentation (決算説明会資料) that Oji Holdings (TSE code 3861) filed on TDnet, the Tokyo Stock Exchange's timely disclosure system, on November 6, 2026. The summaries on this page are in English, and yen figures keep the company's own units, mostly 億円 (¥100 million).
For April-September 2026, net sales rose 430億円 to 9,580億円, operating profit fell 12億円 to 155億円 and interim net profit rose 8億円 to 117億円. Domestic companies earned 199億円 (+18), while overseas companies lost 44億円 (-30), hit by higher raw-material costs tied to the Middle East situation and FX.
Operating profit guidance was lowered from 600億円 to 450億円 because the Middle East situation has lasted longer than expected, pushing up raw-material and fuel costs, and because the pulp market has recovered more slowly. The domestic forecast fell by 40億円 and the overseas forecast by 110億円.
No. Net profit guidance stays at 350億円 because gains on sales of shareholdings offset the operating shortfall, and the FY2026 dividend forecast stays at 36円 per share. The policy is a 50% payout ratio with a floor of 24円 per share.
Oji's fiscal year runs from April to March, so FY2026 is April 2026 to March 2027 and H1 FY2026 (the second quarter cumulative, 2Q累計) covers April to September 2026.
Medium-Term Management Plan 2027 targets are maintained: operating profit of 1,200億円, net profit of 800億円 and ROE of 8%. Cumulative buybacks reached 1,000億円 in May 2026, and the target is 1,500億円 for FY2024-FY2027.
Household & Industrial Materials (containerboard, corrugated, tissue) raised H1 operating profit by 108億円 to 160億円, and Functional Materials rose 29億円 to 83億円. Forest Resources & Environment Marketing (pulp, energy) fell 46億円 to 7億円, and Printing & Communications Media swung to a 16億円 loss.
Yes. It is a clear example of a results deck with an executive summary, price/volume/cost waterfall bridges split by region and segment, sensitivity matrices, guidance-revision tables and a long-term appendix. You can adapt the structure and visual style for your own quarterly results presentation.
Original Japanese-language filing published November 6, 2026

Create Your Own Slides
Turn your ideas into professional presentations in seconds with 2slides AI.
Võta eeskuju professionaalsetest disainidest, vali oma stiil ja genereeri slaidid täiusliku tekstirenderdusega. Nano Banana jõul – alusta oma esitluse loomist kohe.
Sinu AI-agent slaidide loomiseks. Säästa aega ja sära kiiremini nutika esitluste loomisega.


© 2026 2slides. Kõik õigused kaitstud.